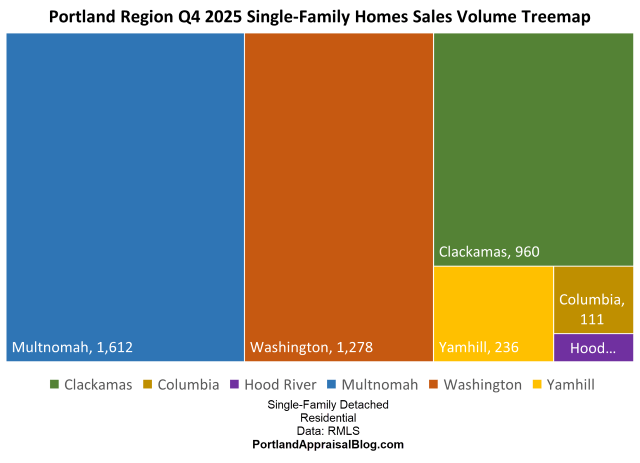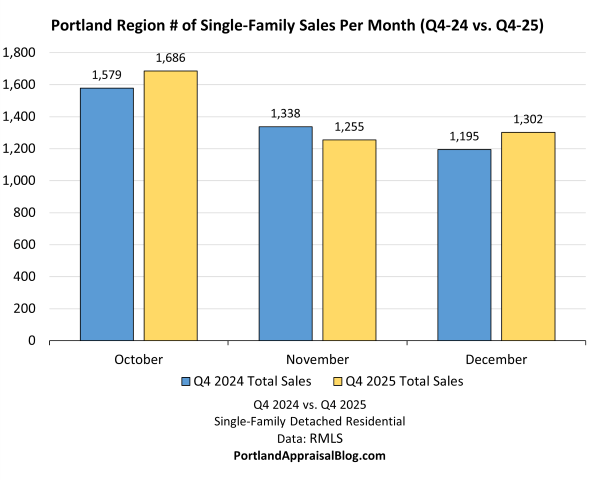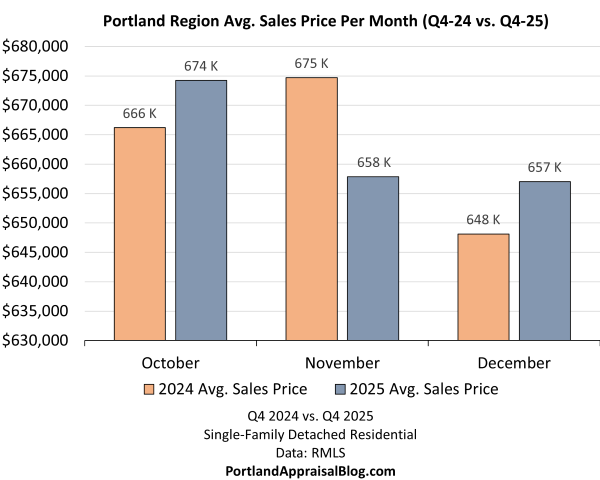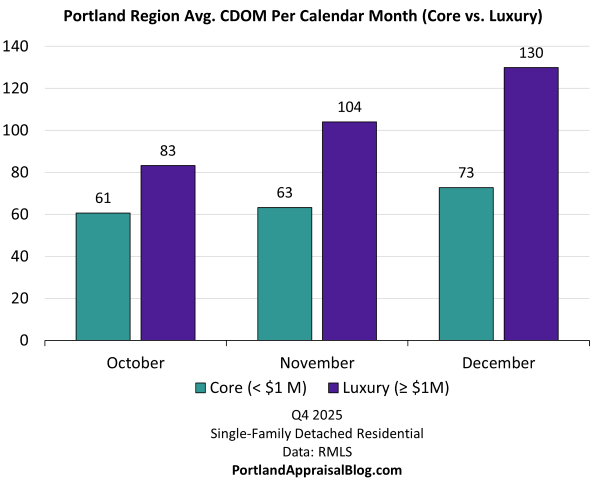Are you an agent in Portland who wonders why appraisers always do “x”?
A homeowner with questions about appraiser methodology?
If so, feel free to reach out—I enjoy connecting with market participants across Portland and the surrounding counties, and am always happy to help where I can.
And if you’re in need of appraisal services in Portland or anywhere in the Portland Region, we’d be glad to assist.
About the Author — Abdur Abdul‑Malik, SRA, ASA
Abdur Abdul‑Malik is the founder, author, and publisher of the Portland Appraisal Blog, where he produces original regional and neighborhood‑level housing analytics for the Portland Region. He is a certified residential appraiser serving Oregon and Washington, drawing on RMLS transaction data, public records, and custom segmentation models he has built.
He developed the Portland Appraisal Blog Affordability Index (PABAI), a payment‑based affordability metric built from actual RMLS sales. PABAI incorporates weekly updates based on the prevailing 30‑year fixed mortgage rate, providing a locally grounded measure of housing affordability across the region.
Q4 2025 Portland Region detached homes update: median price $582k (flat), average $664k (+0.06%), sales volume +3.19%, CDOM rises to 68 days (+16%). County trends, core vs luxury split, appraisal insights, and more.
St. Johns Bridge in the fog—Portland’s northern gateway to neighborhoods full of character and classic detached homes. Via Canva Pro
As the first month of 2026 draws to a close, it’s a natural time to look back at how the Portland Region’s single-family detached home market performed in Q4 2025 (October through December). The data reveals a market that has largely maintained stability despite the ongoing influence of higher interest rates that took hold in 2022 and beyond.
Sellers continue to hold firm, often marketing properties for longer periods to connect with the right buyer and minimize concessions on price. At the same time, buyers have gained slightly more leverage in negotiations, reflecting greater selectivity amid elevated borrowing costs. Core and luxury segments exhibited some distinct patterns in response to these dynamics, yet overall the market appears to have settled into a balanced equilibrium—neither surging nor retreating sharply.
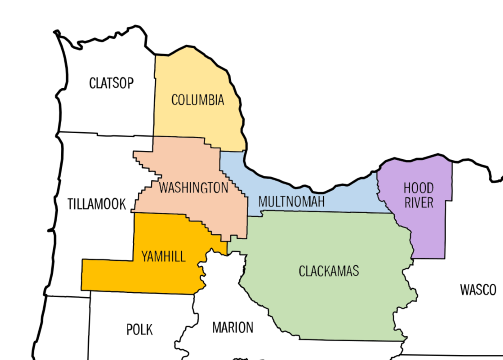
The Portland Region in this update comprises the six Oregon counties of Columbia, Clackamas, Hood River, Multnomah, Washington, and Yamhill. These counties form a contiguous housing ecosystem centered on Portland—Multnomah as the core home county, with the others tightly integrated through commuting patterns, economic ties, and shared market dynamics (e.g., Yamhill’s strong connection via Highway 99W and wine-country adjacency). Beyond Yamhill, the MLS system changes, further distinguishing this six-county area from broader geographic aggregations. For a detailed overview—including county profiles, population data, key value influencers, and why this definition differs from the official seven-county Portland–Vancouver–Hillsboro MSA—see my dedicated page: The Portland Region – Six-County Market Area Overview.
All data is sourced from RMLS and reflects open-market detached single-family residential sales (excluding condos, attached homes, manufactured homes on leased land, and multifamily). SNL (“Sold Not Listed”) entries—off-market transactions entered retroactively—have been excluded to preserve consistency with true market activity.
All figures have undergone my standard cleaning process to address common RMLS accuracy challenges, including misclassifications (e.g., condos listed as detached), square footage/price typos, incomplete fields, status/date mismatches, and non-representative entries. For a detailed overview of these issues, their impact on market analysis, and how I mitigate them through automated flagging, cross-verification, and manual review, see my dedicated page: RMLS Data Accuracy Challenges.
Portland Region 2025 Q4 Overview
The Q4 2025 detached single-family home market in the six-county Portland Region showed signs of continued stabilization. After several quarters of adjustment to elevated interest rates, the data reflects a market that has found a tentative balance—neither accelerating nor declining sharply. Volume edged higher year-over-year, while price metrics remained essentially flat, and days on market continued to lengthen, pointing to buyer selectivity and seller patience.
Overall Regional Trends
The table below summarizes key metrics for detached single-family residential sales in the Portland Region (Columbia, Clackamas, Hood River, Multnomah, Washington, and Yamhill counties) for Q4 2025 compared with Q4 2024.
Sales count rose modestly (+3.19%), driving the overall volume increase (+3.25%), while both average and median prices were virtually unchanged.
The slight decline in average PPSF (-1.30%) appears largely compositional: average square footage increased +1.83%, and larger homes typically carry lower PPSF unless offset by luxury or new-construction premiums.
Average cumulative days on market increased significantly (+16.32% to 68.45 days), consistent with buyers remaining selective under higher borrowing costs and sellers holding firm rather than conceding aggressively (reflected in the modest drop in SP/OLP ratio to 95.72%).
New construction volume retreated further (-4.14%), though the year-over-year drop was less severe than in Q3 2025.
Distressed activity (REOs + short sales) ticked up to approximately 1.18% of total sales (from 0.61% in Q4 2024), but remains negligible in the broader market context.
Bottom-line Summary
If the Portland Region housing market were a ship, Q4 2025 would be described as “steady as she goes.” The vessel is neither listing sharply nor picking up speed; it is maintaining course through persistent headwinds from higher interest rates. Sellers are exercising patience by allowing longer marketing periods, buyers are exercising discretion by negotiating more effectively, and price levels are holding firm despite the extended exposure time. This equilibrium suggests a market that has largely absorbed the rate shock of 2022–2023 and is now operating in a more normalized, balanced state—albeit one where momentum is subdued and selectivity is elevated.
Core Market (< $1M)
The core market—detached single-family homes closing under $1 million—accounts for the overwhelming majority of transactions in the region (91.35% of sales count and 80.55% of dollar volume in Q4 2025). This segment largely drives the overall picture of stability described earlier, with year-over-year changes that are muted but revealing of ongoing buyer caution.
The table below shows core-market metrics for Q4 2025 compared with Q4 2024.
The core segment saw a healthy increase in transaction volume (+3.30% in sales count), which translated directly to the modest dollar-volume growth (+3.31%). Price levels, however, remained essentially flat—average price up a negligible 0.01%, median price down slightly (-0.49%). This stability at the median level aligns with the broader regional pattern and suggests that the typical buyer in this price band is still finding properties within reach despite elevated rates.
The most noticeable movement appears in market tempo. Average cumulative days on market climbed +20.20% to 65.25 days, a sharper rise than the regional average as a whole. Buyers in this price-sensitive segment are clearly taking more time to commit, inspecting more options, and negotiating more effectively—the modest decline in the SP/OLP ratio (97.09% → 96.03%) reflects that added leverage. Sellers, meanwhile, appear willing to wait rather than drop asking prices aggressively.
The slight drop in average PPSF (-1.41%) is again largely explained by compositional factors: homes closing in Q4 2025 were, on average, 41 square feet larger (+2.08%). Larger floor plans naturally dilute PPSF unless premium finishes or locations offset the effect, which does not appear to be the case here on a broad scale.
New construction in the core market held up reasonably well, with only a -1.62% drop in count year-over-year. This modest retreat contrasts with sharper declines seen in prior quarters and suggests builders are still finding demand for entry-to-mid-level new homes, even as overall supply pressures ease slightly.
Overall, the core market continues to reflect the realities of affordability-conscious buyers navigating higher borrowing costs: more transactions at stable prices, but with extended decision time and a bit more negotiating power on the buyer side.
Luxury Market (≥ $1M)
The luxury segment—detached single-family homes closing at or above $1 million—remains a smaller but influential portion of the regional market, representing 8.65% of sales count and 19.45% of total dollar volume in Q4 2025. While the core market drives the headline numbers on volume and stability, the luxury segment often reveals early signals of shifting buyer sentiment and supply constraints.
The table below shows luxury-market metrics for Q4 2025 compared with Q4 2024.
The luxury segment posted modest gains in both transaction count (+1.94%) and dollar volume (+2.98%), which translated to small but positive price movement: average price up +1.02% and median price up +1.42%. This slight upward pressure contrasts with the flat pricing seen in the core market and contributed an additional ~$15.9 million in total seller proceeds compared with Q4 2024 in this segment.
Market tempo improved somewhat for luxury properties. Average cumulative days on market fell -3.90% to 102.2 days—the only segment to see a reduction in exposure time. This suggests that well-positioned high-end homes are still finding motivated buyers relatively efficiently, even as the broader market lengthens. The SP/OLP ratio continued to soften slightly (93.22% → 92.43%), indicating that sellers in this price band are conceding a bit more ground to close deals.
The most striking shift occurred in new construction. The number of new luxury homes closing dropped sharply (-25.5%), from 51 to 38. This retreat is significantly steeper than the core segment’s mild -1.62% decline and continues a multi-quarter trend of reduced high-end speculative building. Builders appear to be pulling back from the upper end, possibly due to financing costs, buyer selectivity, or uncertainty around future demand.
Another notable change is the jump in average age of sold properties (+15.40% to 43.61 years). A key driver here is the sharp retreat in new construction (-25.49%, from 51 to 38 closings). New homes typically enter and close with near-zero age, pulling the average down when they represent a meaningful share of sales. With far fewer new builds closing this quarter, the sales mix shifted toward existing (and generally older) properties, naturally increasing the average age of transactions. PPSF remained virtually flat (-0.08%), and average square footage edged up modestly (+1.07%), indicating that luxury buyers are not trading down on size or quality but are closing on a different mix of inventory.
From an appraisal perspective, the luxury market’s relative resilience on pricing and CDOM improvement provides a useful contrast for comp selection and market-condition adjustments. However, the sharp drop in new construction supply at this price point may begin to influence highest-and-best-use considerations and functional obsolescence assessments for older luxury improvements in the coming quarters.
Sales Volume
A treemap visualizing the distribution of detached single-family home sales by county in Q4 2025 clearly illustrates the market’s geographic concentration.
The “Big Three” counties—Multnomah, Washington, and Clackamas—account for over 90% of total transactions and dollar volume, underscoring their role as the dominant drivers of regional activity. Multnomah leads in sheer number of sales (37.99% of the total), followed closely by Washington (30.12%) and Clackamas (22.63%). The remaining three counties (Yamhill, Columbia, and Hood River) together represent less than 10% of sales, highlighting the highly urban/suburban focus of the Portland Region’s detached home market.
The bar chart below compares monthly sales volume across the three months of Q4 for 2024 and 2025.
Monthly sales patterns show a mixed picture compared with last year. October 2025 posted a noticeable increase (1,686 vs. 1,579), helping drive the overall quarterly gain in transaction volume. November softened relative to 2024 (1,255 vs. 1,338), reflecting typical holiday slowdown effects, while December rebounded (1,302 vs. 1,195), closing the quarter on a stronger note. The net result is a modest year-over-year increase in total sales (4,243 vs. 4,112), consistent with the regional stabilization theme.
Sales Price
The bar chart below compares monthly average sales prices across the three months of Q4 for 2024 and 2025.
Note: The y-axis starts at $630,000 to allow better examination of monthly differences.
Average sales prices showed only minor month-to-month variation compared with the prior year. October 2025 posted a modest increase over October 2024 ($674,243 vs. $666,189), while November softened ($657,867 vs. $674,704). December then rebounded slightly ($657,031 vs. $648,133). These movements align with the overall quarterly stability, where the average price ended virtually unchanged (+0.06% for the full quarter) despite the shifting monthly pattern. The lack of significant upward or downward momentum reinforces the sense of equilibrium reached in the market after several years of rate-driven adjustment.
New Construction
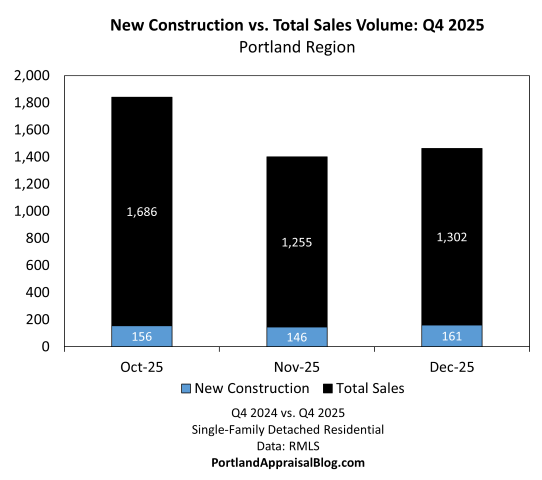
The bar graph below shows monthly total detached single-family sales in Q4 2025, with new construction volume nested within each bar to illustrate the portion of sales that were newly built.
New construction remained a relatively small but visible share of overall activity in Q4 2025, averaging 10.91% of total sales for the quarter. Monthly percentages ranged from 9.25% in October to 12.37% in December, reflecting some seasonal pickup toward year-end. The absolute count of new homes closing (463) was down modestly from Q4 2024 (483, -4.14%), continuing the multi-quarter retreat in new supply observed earlier in the year. This reduction has contributed to the gradual tightening of inventory in certain segments and price bands, particularly at the luxury end where the drop was more pronounced.
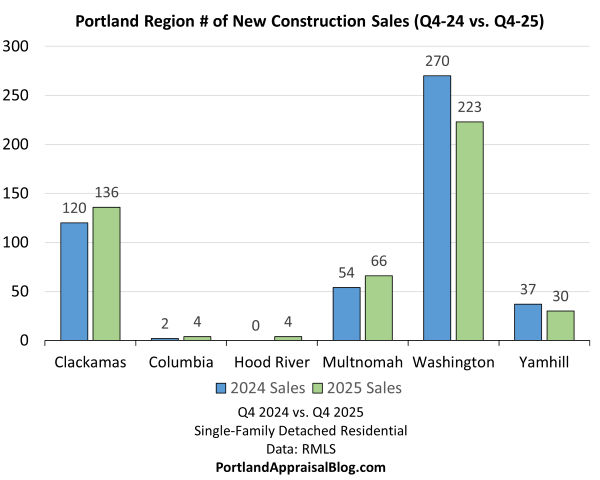
A county-level breakout of new construction sales volume in Q4 2025 compared with Q4 2024 reveals significant variation across the region. The bar graph below shows the number of new construction closings by county, with side-by-side bars for 2024 and 2025.
Washington County continued to lead in absolute new construction volume (223 closings in 2025, 48.16% of the regional total), though it experienced the largest absolute drop (-47 units, -17.41%). Clackamas posted the strongest percentage gain (+13.33%) and now represents nearly 30% of all new closings. Multnomah showed solid growth (+22.22%), while Yamhill, Columbia, and Hood River remained small contributors, with Hood River moving from zero to four closings.
The overall regional decline in new construction (-4.14%) masks these internal shifts. The concentration in Washington and Clackamas reflects ongoing builder focus on suburban growth corridors, while the limited activity in outer counties highlights the challenges of scaling new supply in lower-volume, more rural submarkets.
Clackamas County’s recent gain in new construction share (now 29.37% of regional total) may prove short-lived. The ongoing sewer moratorium in Sandy, Oregon—one of the county’s primary growth areas—has already begun to constrain the new-home pipeline. Sandy historically averaged 27% new construction annually for its total sales count over a 28-year period, significantly exceeding available sewer capacity. With the remaining approved projects expected to close by late 2026 or early 2027, Clackamas’s contribution to regional new supply is likely to shrink in the coming quarters. For a full analysis of this shift and its implications for local market dynamics, see my recent deep dive: Sandy Oregon’s Sewer Moratorium.
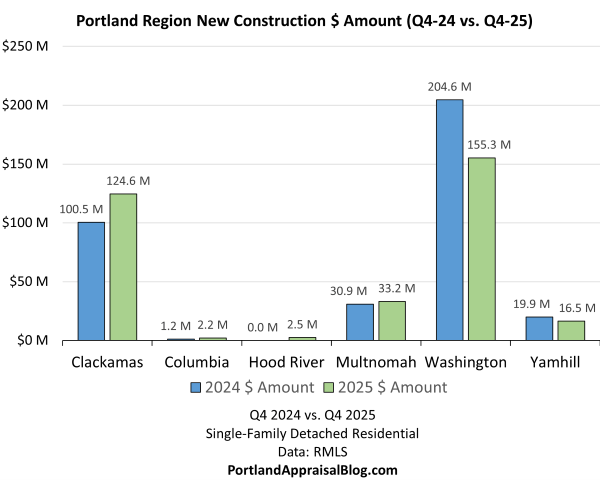
The dollar value of new construction closings provides additional context on builder activity and investment scale. The table below shows new construction sales volume by dollar amount for Q4 2025 compared with Q4 2024.
The following double bar chart provides the above information at a glance.
While the count of new construction closings fell modestly (-4.14%), the dollar volume declined more noticeably (-6.39% regionally), reflecting a shift toward relatively lower-priced new homes or fewer ultra-high-end builds. Washington County again dominated in absolute dollars ($155.3M, 5.51% of the total regional value) but saw the largest year-over-year drop (-$49.3M, -24.10%). Clackamas posted the strongest dollar gain (+$24.1M, +23.99%), taking a larger slice of the shrinking pie. These patterns highlight ongoing builder caution in higher-cost segments and continued focus on suburban growth corridors.
Cumulative Days on Market
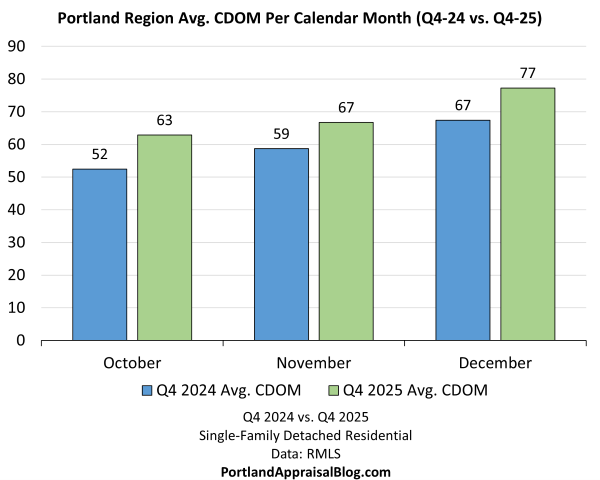
The bar chart below compares average cumulative days on market (CDOM) across the three months of Q4 for 2024 and 2025.
Average cumulative days on market rose across every month in Q4 2025 compared with the prior year, with increases ranging from 13.74% in November to 19.83% in October. The quarterly average CDOM climbed +16.32% overall (58.84 → 68.45 days), reflecting sustained buyer selectivity amid elevated interest rates. Sellers have responded by allowing longer marketing periods rather than making aggressive price concessions, contributing to the market’s current equilibrium. This extended exposure time is a key signal for appraisers when assessing comparable freshness and applying market-condition adjustments in valuations.
The bar chart below breaks out average CDOM by market segment for the three months of Q4 2025, comparing core (< $1M) and luxury (≥ $1M) properties.
Core-market CDOM rose steadily from 61 days in October to 73 days in December, reflecting the price-sensitive nature of the segment and buyers taking more time to commit. Luxury-market CDOM showed a similar upward trend but from a much higher baseline, increasing from 83 days in October to 130 days in December. The persistent and larger gap between the two segments indicates that luxury buyers remain more selective and willing to wait for properties that precisely match their criteria, even as overall market tempo has slowed, and also the difficulties in finding a buyer than can afford homes in this segment.
Miscellaneous Statistics & Standout Transactions
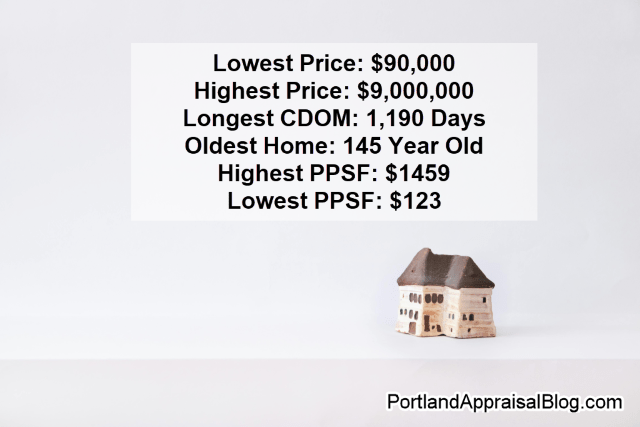
A few notable extremes and outliers from Q4 2025 illustrate the wide range of value drivers across the six-county region.
Lowest close price: $90,000—a 1930s fixer cabin in Forest Grove (Washington County). The property offered original character but required extensive rehabilitation, including interior plumbing repairs and floor work. Photos of this property are currently available online.
Highest close price: $9,000,000—a lakefront estate in Lake Oswego (Clackamas County). The custom-built residence featured premium waterfront amenities, including a private dock, boathouse, and expansive outdoor entertaining spaces. Photos of this property are currently available online.
Longest CDOM: 1,190 days—a $1.9M listing in Multnomah County (Alphabet District) that closed at $1.35M. The 2017-remodeled oversized bungalow included modern updates and a separate ADU, yet required multiple price reductions before finding a buyer. Photos of this property are currently available online.
Oldest home sold: Built in 1881—located in Oregon City (Clackamas County). This restored Italianate two-story featured high ceilings, new hardwood floors, and a complete modern kitchen, blending historic character with contemporary systems. Photos of this property are currently available online.
Highest PPSF: $1,459—a small home on 82 acres in Multnomah County. The elevated price per square foot was driven primarily by the large acreage and historic outbuildings rather than the modest improvements. Photos of this property are currently available online.
Lowest PPSF: $123—an REO (bank-owned) sale in Clatskanie (Columbia County). The 2-story home with basement needed significant restoration, with the low per-square-foot price reflecting condition challenges and rural location. Photos of this property are currently available online.
These outliers demonstrate that detached single-family home ownership in the Portland Region can begin around $100,000 for buyers who are patient, flexible, and prepared to address condition or location factors. They stand in contrast to the region’s severely strained affordability, as measured by the Portland Appraisal Blog Affordability Index (PABAI), which stood at 79.2 for Q4 2025. For the full methodology and discussion, see the dedicated page: Portland Appraisal Blog Affordability Index – PABAI. A comprehensive review of 2025 affordability trends is forthcoming.
With the regional aggregate trends, segment splits, monthly patterns, and notable outliers now in view, the remainder of this update turns to a county-level breakdown. The following sections present year-over-year comparisons for each of the six counties in the Portland Region—Multnomah, Washington, Clackamas, Yamhill, Columbia, and Hood River—ordered by Q4 2025 sales volume descending. Each county snapshot includes key metrics, commentary on local drivers, and any segment-specific observations that help explain broader regional patterns.
Multnomah County Q4 2025 Stats
Multnomah County, the urban core of the Portland Region, led in detached single-family home transaction volume for Q4 2025 with 1,612 sales—representing 37.99% of the regional total and a 5.29% increase from Q4 2024. Despite the high count, average and median prices remained below regional figures, reflecting the county’s mix of older homes, smaller lots, and more modest price bands in established neighborhoods.
The table below summarizes key metrics for Multnomah County detached single-family residential sales in Q4 2025 compared with Q4 2024.
Multnomah County’s market tempo remained the fastest in the region, with average cumulative days on market at 54.48 days—well below the regional average of 68.45 days. This shorter exposure time reflects sustained urban demand in walkable neighborhoods such as the Alphabet District, Pearl, and inner-eastside areas, where proximity to amenities and transit continues to draw buyers despite elevated rates. The modest rise in CDOM (+4.79%) was less pronounced than the regional increase (+16.32%), indicating relatively stronger buyer interest and quicker decision-making in the core.
Price metrics showed slight upward movement: average price +0.92% to $611,760 and median price +0.71% to $533,750. The SP/OLP ratio softened marginally (97.06% → 96.63%), suggesting buyers retained some negotiating leverage even in a high-volume market. Average PPSF edged up +0.30%, despite the small increase in average square footage (+0.46%). The PPSF increase was likely due to the lot size increase (+11.38%), though the county’s older housing stock (average age 66.30 years) continues to temper broader price gains.
New construction activity increased +22.22% (66 closings), rebounding from a sharp -48% year-over-year drop in Q3 2025. Despite the gain, new builds remained a small share (4.1% of county sales), underscoring persistent infill constraints and builder focus on suburban corridors elsewhere. Distressed sales ticked up (REOs +171.43%, short sales +33.33%), though absolute numbers stayed low and did not materially influence the overall market.
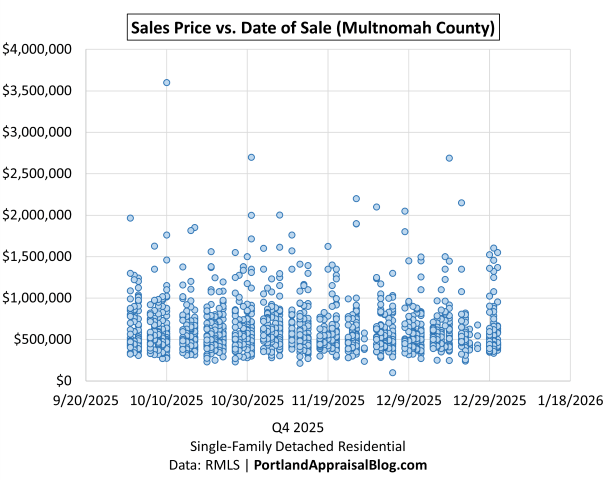
A scatter plot of all Multnomah County sales in Q4 2025 (close price vs. date of sale) shows no strong upward or downward trend across the quarter.
The distribution clusters primarily in the $400k–$800k range with CDOM generally under 100 days, consistent with the county’s efficient urban tempo. A modest number of sales appear above $1.5M, with one notable outlier closing above $3.5M, reflecting continued activity at the upper end despite the broader market’s stability.
From an appraisal perspective, Multnomah County’s combination of high transaction volume, shorter CDOM, and modest price growth provides a stable benchmark for comp selection in urban submarkets. The limited new supply and aging inventory require careful adjustments for condition, functional obsolescence, and location premiums, while the scatter of higher-end sales suggests selective but persistent demand above $1.5M.
Washington County Q4 2025 Stats
Washington County ranked second in detached single-family home transaction volume for Q4 2025 with 1,278 sales (30.12% of the regional total), up +7.58% from Q4 2024. The county experienced noticeable price softening alongside longer market times, reflecting a shift in buyer behavior and supply dynamics in this suburban growth corridor.
The table below summarizes key metrics for Washington County detached single-family residential sales in Q4 2025 compared with Q4 2024.
Transaction volume grew solidly (+7.58%), driving a modest increase in total dollar volume (+2.92%). However, both average and median prices declined noticeably (-4.33% and -3.20%, respectively), and average PPSF fell -4.45%. This softening appears partially compositional: new construction retreated sharply (-17.41%, 270 → 223 closings), removing a number of higher-priced new builds from the sales mix. The remaining closings skewed toward older homes (average age +10.67% to 32.39 years) and larger lots (+14.24%), which typically carry lower PPSF in this market.
The weakening in average and median prices can be partially explained by the impact of job loss in Hillsboro. External obsolescence tied to Intel’s 2024–2025 workforce reductions has contributed to declining resale prices and buyer confidence in certain segments. For a detailed analysis of resale trends, condominium/attached impacts, and appraisal implications in Hillsboro, see my recent deep dive: External Obsolescence in Hillsboro — Residential Market Response to Intel’s 2024–2025 Workforce Reductions.
Market tempo slowed significantly, with average cumulative days on market rising +24.49% to 74.24 days—among the longest in the region and well above the prior year’s level. This extension, combined with a softer SP/OLP ratio (97.13% → 95.50%), indicates buyers were more selective and willing to wait, particularly in a county heavily influenced by tech employment centers like Hillsboro.
Distressed activity remained low in absolute terms but showed directional movement (REOs +250.00% to 7, short sales -100.00% to 0), consistent with broader regional patterns where condition-related sales are still rare but present.
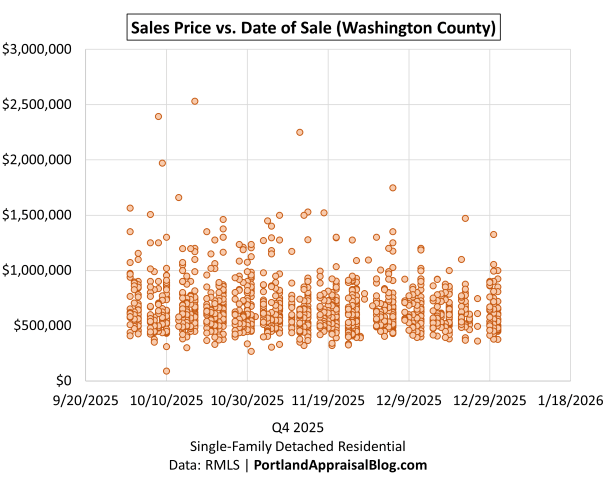
A scatter plot of all Washington County sales in Q4 2025 shows no strong upward or downward trend overall.
The vast majority of transactions cluster between the high $400,000s and just under $1 million, reflecting the county’s primary move-up and family-oriented price band. Activity thins noticeably above $1 million, with only a handful of points in the $1.5M+ range and just three sales exceeding $2 million, underscoring limited buyer participation at the true upper end of the market.
From an appraisal perspective, Washington County’s volume growth amid price softening and extended CDOM highlights the importance of segment-specific adjustments when selecting comparables. The retreat in new construction and shift toward older/larger existing homes may affect functional obsolescence assessments and market-condition time adjustments, particularly in submarkets sensitive to employment stability.
Clackamas County Q4 2025 Stats
Clackamas County ranked third in detached single-family home transaction volume for Q4 2025 with 960 sales (22.63% of the regional total), down slightly -1.13% from Q4 2024. Despite the modest volume decline, the county showed resilience in pricing, with both average and median prices posting gains amid longer market times.
The table below summarizes key metrics for Clackamas County detached single-family residential sales in Q4 2025 compared with Q4 2024.
Clackamas County bucked the regional trend of price stability or softening, with average price up +1.40% to $784,904 and median price up +3.90% to $650,000—the highest median among the six counties. This upward movement occurred despite a slight decline in sales count and a modest drop in PPSF (-0.35%), supported by a small increase in average square footage (+2.06%). The notable reduction in average lot size (-22.65%) appears driven by a compositional shift toward smaller-lot sales in premium and growth-oriented submarkets (e.g., Lake Oswego, West Linn, Happy Valley, Wilsonville), where demand remained strong and prices held firm or increased. New construction gains (+13.33%, 120 → 136 closings) were concentrated in these same corridors (Happy Valley, Wilsonville, Canby, Sandy), adding higher-priced units on compact lots and helping offset softness in more rural areas with larger parcels.
Market tempo slowed, with average cumulative days on market rising +18.80% to 78.50 days—above the regional average. This extension, paired with a softer SP/OLP ratio (96.02% → 94.95%), indicates buyers exercised greater selectivity, though price gains suggest demand held firm in desirable submarkets.
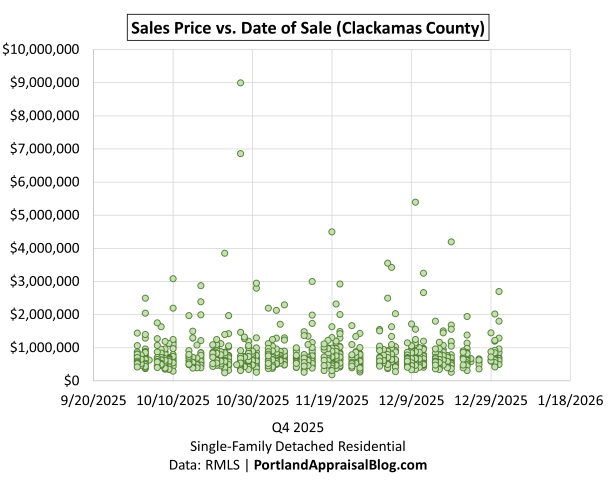
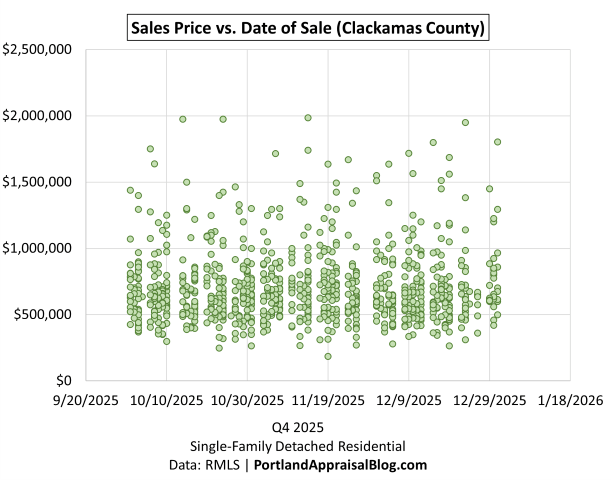
A scatter plot of all Clackamas County sales in Q4 2025 shows no major upward or downward trend overall.
The bulk of transactions cluster between roughly $400k and $1M, with activity thinning considerably above $1 million. Clackamas stands out regionally for its active high-end market, with 30 sales at or above $2M (including the county’s top sale of $9M in Lake Oswego)—far more than any other county. When slicing away these extreme outliers above $2M (leaving 930 data points), the distribution remains flat with no clear directional pattern, consistent with balanced mid-market performance.
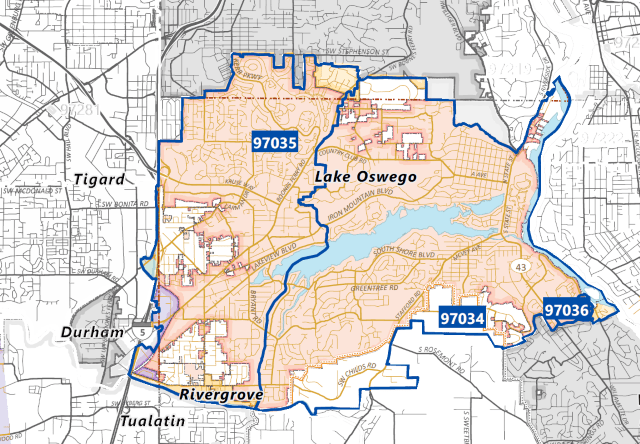
Lake Oswego ZIP codes 97034 and 97035 rank #1 and #3 among areas with appreciable sales volume in the Portland Region, underscoring their role in anchoring the county’s price resilience.
ZIP code map of 97034 & 97035, ranking #1 and #3 is average sales price for ZIP codes with appreciable volume. Map via Oregonmetro.gov
From an appraisal perspective, Clackamas County’s price gains amid longer CDOM and reduced lot sizes highlight the need for careful location and size adjustments in comp selection.
Yamhill County Q4 2025 Stats
Yamhill County ranked fourth in detached single-family home transaction volume for Q4 2025 with 236 sales (5.56% of the regional total), down -9.58% from Q4 2024. The county showed modest price gains despite the volume decline, reflecting a shift toward larger-lot and higher-value closings.
The table below summarizes key metrics for Yamhill County detached single-family residential sales in Q4 2025 compared with Q4 2024.
Category
Q4 2024
Q4 2025
% Change
Total $ Volume
$145 Million
$139 Million
-4.18%
Average Price
$555,905
$589,101
+5.97%
Median Price
$509,900
$515,000
+1.00%
Avg SP/OLP
96.59%
95.01%
-1.63%
Avg PPSF (TSF)
$305.05
$312.27
+2.37%
Avg Lot Size (ac)
1.49
2.05
+37.40%
Avg Age (Yrs)
36.75
35.60
-3.13%
Avg CDOM
61.02
79.34
+30.03%
Avg Total SF
1,866
1,956
+4.81%
# of Sales
261
236
-9.58%
# of New Constr.
37
30
-18.92%
# of REOs
2
1
-50.00%
# of Short Sales
1
3
+200.00%
Yamhill County saw a decline in sales count (-9.58%) and total dollar volume (-4.18%), but average price rose +5.97% to $589,101 and median price increased +1.00% to $515,000. This upward movement in pricing was largely compositional: average lot size increased significantly (+37.40% to 2.05 acres) and average square footage rose +4.81%, shifting the sales mix toward larger properties that typically command higher prices in this rural/suburban county. Average PPSF edged up +2.37%, consistent with the larger parcels and slightly newer homes (average age down -3.13% to 35.60 years).
Market tempo slowed considerably, with average cumulative days on market rising +30.03% to 79.34 days—one of the longer exposures in the region. The softer SP/OLP ratio (96.59% → 95.01%) suggests buyers were more selective and willing to negotiate, particularly in a lower-volume county with limited new supply.
New construction continued to retreat (-18.92%, 37 → 30 closings), with Lafayette capturing the majority (21 of 30 county-wide new homes), likely reflecting the final phase of a small subdivision in this growing but still small community.
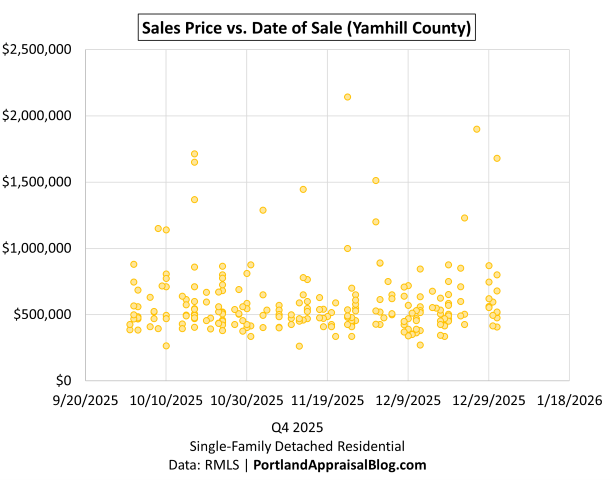
A scatter plot of all Yamhill County sales in Q4 2025 shows no strong upward or downward trend overall.
The vast majority of transactions cluster between $400,000 and $700,000 (approximately 61% of sales fall in the $400k–$599k bands), reflecting the county’s primary mid-market focus. Activity thins considerably above $800,000, with only a handful of sales reaching $1 million and just one exceeding $2 million, underscoring limited buyer participation at the upper end.
From an appraisal perspective, Yamhill County’s modest price gains amid declining volume and extended CDOM highlight the importance of size and location adjustments in comp selection. The shift toward larger lots and the retreat in new construction may affect supply considerations and functional obsolescence assessments in this more rural county, while the mid-market concentration provides a stable base for typical valuations.
Columbia County Q4 2025 Stats
Columbia County ranked fifth in detached single-family home transaction volume for Q4 2025 with 111 sales (2.62% of the regional total), down -9.02% from Q4 2024. The county showed modest price gains despite the volume decline, reflecting a shift toward larger homes in this more rural area.
The table below summarizes key metrics for Columbia County detached single-family residential sales in Q4 2025 compared with Q4 2024.
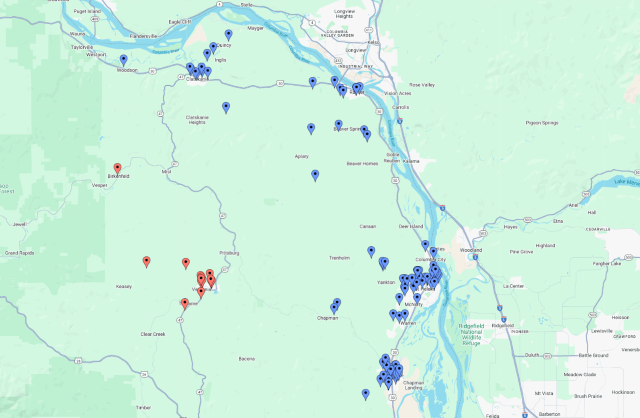
Columbia County’s sales activity is overwhelmingly concentrated along the Columbia River corridor (e.g., St. Helens, Scappoose, Rainier, Columbia City, Deer Island, and Clatskanie), with approximately 97 of the 111 sales occurring in these river-adjacent areas. This geographic focus aptly reflects the county’s name and population distribution.
Average price rose +3.33% to $505,417 and median price increased +4.88% to $480,000 despite a decline in sales count and total dollar volume (-5.99%). This upward movement in pricing was largely compositional: average square footage increased +11.02%, shifting the sales mix toward larger homes that command higher prices in this rural county. Average PPSF fell -3.06%, consistent with the larger floor plans and slightly smaller lots (-9.00%), while average age remained stable (49.14 years).
Market tempo slowed, with average cumulative days on market rising +11.45% to 83.37 days—one of the longer exposures in the region. The softer SP/OLP ratio (95.69% → 94.58%) suggests buyers were more selective, particularly in a lower-volume county with limited new supply.
New construction remained minimal but doubled (2 → 4 closings), a small absolute increase that did not materially impact the overall market. Distressed activity stayed low (REOs -50.00% to 2, short sales 0).
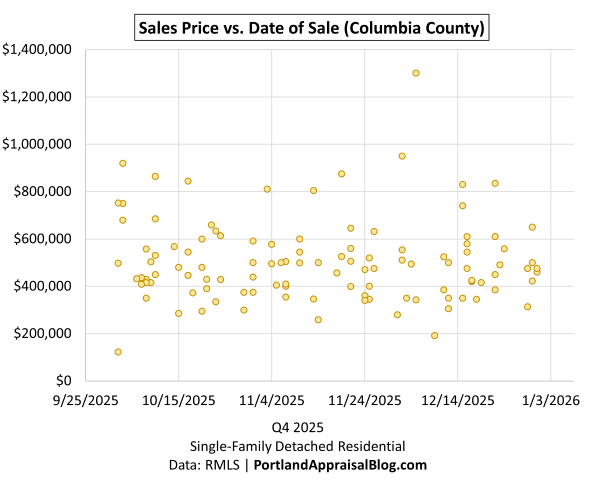
A scatter plot of all Columbia County sales in Q4 2025 shows no major upward or downward trend overall.
The bulk of transactions cluster between roughly $300k and $600k (approximately 72% of sales fall in the $300k–$599k bands), reflecting the county’s primary mid-market, rural focus. Activity thins considerably above $700k, with only a small number of sales reaching $800k–$900k and one sale above $1 million, underscoring limited buyer participation at the upper end of the market.
From an appraisal perspective, Columbia County’s modest price gains amid declining volume and extended CDOM highlight the influence of property size and location in rural submarkets. The shift toward larger homes and limited new construction require careful adjustments for the contributory value of additional square footage and condition when selecting comparables.
Hood River County Q4 2025 Stats
Hood River County ranked sixth in detached single-family home transaction volume for Q4 2025 with 46 sales (1.08% of the regional total), up +17.95% from Q4 2024. The county posted strong gains in both volume and pricing, reflecting robust demand in this scenic, smaller market.
The table below summarizes key metrics for Hood River County detached single-family residential sales in Q4 2025 compared with Q4 2024.
Hood River County saw notable growth in sales count (+17.95%) and total dollar volume (+53.86%), with average price rising +30.44% to $898,167 and median price up +6.44% to $729,125—the highest median in the region. This strong upward pressure was largely compositional: average lot size increased dramatically (+649.39% to 2.43 acres) and average square footage rose +28.83%, shifting the sales mix toward larger properties that command premium prices in this scenic, rural county. Average PPSF declined -7.85%, consistent with the much larger lots and floor plans.
Market tempo slowed significantly, with average cumulative days on market rising +60.77% to 95.39 days—one of the longest exposures in the region. The softer SP/OLP ratio (95.42% → 92.49%) suggests buyers exercised greater selectivity, even as price gains indicate sustained demand for desirable properties.
New construction emerged from zero in Q4 2024 to 4 closings in Q4 2025, a small but positive increase in this low-volume county. Distressed activity remained nonexistent (REOs and short sales zero both quarters).
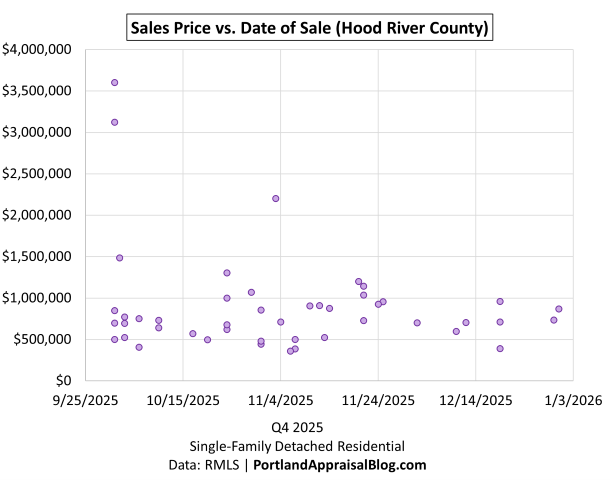
A scatter plot of all Hood River County sales in Q4 2025 shows no strong upward or downward trend overall.
The bulk of transactions cluster in the $500k–$1M range, with decent activity above $1M and three sales exceeding $2M—impressive for a county with only 46 total closings. The lowest sale was $360,000, reflecting limited low-end inventory in this scenic market.
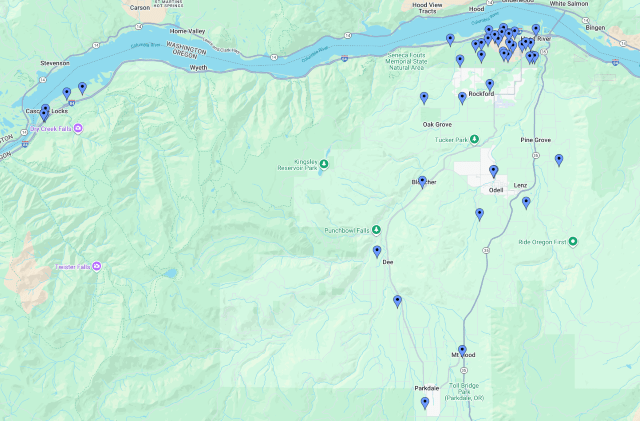
Sales are heavily concentrated in and around Hood River city (including many properties with Hood River addresses but outside official city limits), underscoring the area’s role as the county’s primary population and housing hub.
From an appraisal perspective, Hood River County’s sharp price and volume gains amid longer CDOM and much larger lots highlight the influence of property size and scenic/rural appeal in this smaller market. The emergence of new construction and extended exposure time require careful adjustments for condition, location premiums, and lot size when selecting comparables.
Closing Thoughts
The Portland Region’s detached single-family home market in Q4 2025 displayed clear signs of stabilization after several quarters of adjustment to higher interest rates. Transaction volume edged higher (+3.19%), prices held essentially flat at the median ($582,000) and showed only marginal movement at the average (+0.06%), and days on market continued to lengthen (+16.32% to 68.45 days), reflecting sustained buyer selectivity and seller patience. The core market (< $1M) drove most of the activity while showing more pronounced tempo slowdowns, while the luxury segment (≥ $1M) exhibited relative resilience in pricing and shorter exposure in some cases, though with sharper retreats in new construction supply.
County-level patterns varied, with the urban core (Multnomah) maintaining the fastest tempo and high volume, suburban Washington and Clackamas showing mixed softening and resilience respectively, and the outer counties (Yamhill, Columbia, Hood River) demonstrating more pronounced compositional shifts and longer marketing times. Overall, the market has reached a balanced equilibrium—neither surging nor retreating sharply—yet the extended exposure times and segment-specific supply constraints remain key signals for appraisers, lenders, and realtors navigating valuations and decisions in the coming quarters.
What trends do you expect to see in Q1 2026? I’d love to hear your thoughts—feel free to reply here or reach out directly.
Sources & Further Reading
All data presented in this quarterly update is sourced directly from RMLS and has been subjected to my rigorous cleaning and validation process to ensure reliability for detached single-family residential analysis in the six-county Portland Region. The trends, comparisons, and commentary are the result of original appraisal expertise and independent analysis—not aggregated from secondary sources or news summaries.
Sandy Oregon’s Sewer Moratorium — The End of a 27-Year New Construction Boom: Portland Appraisal Blog
External Obsolescence in Hillsboro — Residential Market Response to Intel’s 2024–2025 Workforce Reductions: Portland Appraisal Blog
Portland Affordability Index – PABAI: A Realistic Housing Qualification Metric for the Portland Region: Portland Appraisal Blog
Coda
Thanks for reading—I hope you found a useful insight or an unexpected nugget along the way. If you enjoyed the post, please consider subscribing for future updates.
Are you an agent in Portland who wonders why appraisers always do “x”?
A homeowner with questions about appraiser methodology?
If so, feel free to reach out—I enjoy connecting with market participants across Portland and the surrounding counties, and am always happy to help where I can.
And if you’re in need of appraisal services in Portland or anywhere in the Portland Region, we’d be glad to assist.
About the Author — Abdur Abdul‑Malik, SRA, ASA
Abdur Abdul‑Malik is the founder, author, and publisher of the Portland Appraisal Blog, where he produces original regional and neighborhood‑level housing analytics for the Portland Region. He is a certified residential appraiser serving Oregon and Washington, drawing on RMLS transaction data, public records, and custom segmentation models he has built.
He developed the Portland Appraisal Blog Affordability Index (PABAI), a payment‑based affordability metric built from actual RMLS sales. PABAI incorporates weekly updates based on the prevailing 30‑year fixed mortgage rate, providing a locally grounded measure of housing affordability across the region.
Q3 2025 RMLS data shows the Portland Region’s detached starter homes (5th–35th percentile) average $469k and are dominated by mid-century builds on larger lots—with new construction offering modern features but far less space. Appraisal and buyer insights below.
A classic early-20th-century bungalow in the Portland area—the type of modest, well-loved home that dominates today’s starter-tier inventory. Via Canva Pro
Earlier this month, Redfin highlighted Portland as one of the stronger markets nationally for starter-home activity, defining starter homes as sales in the 5th–35th percentile by price. We adopt the same percentile convention here for consistency.
Redfin’s reported median of approximately $420,000 for Portland starter homes includes all property types (condos, townhomes, and single-family). Focusing solely on detached single-family residences—a popular choice across the region, including for many urban buyers seeking yard space and privacy over attached ownership—Q3 2025 RMLS data for the 5th–35th percentile tier shows an average close price of $469,000.
Few would be surprised that new construction plays a limited role in true entry-level pricing—after all, building costs remain elevated. Yet the data shows builders are still delivering a modest but meaningful number of brand-new homes into this tier (about 4.2% of starter sales, compared to 9.1% across the full market). This demonstrates that, through efficient design, infill strategies, and lot divisions, new product can compete in the lower price bands.
Local buyers want to know: how much home does a starter budget actually buy? This analysis examines square footage, lot size, build era, and location differences across counties—revealing a market dominated by mid-century homes with a modest but noteworthy presence of brand-new construction.
How Much Home a Starter Budget Buys by County
The table below summarizes Q3 2025 closed sales for detached single-family homes in the 5th–35th percentile across the core Portland Region counties (Hood River row excluded due to only two qualifying sales).
County
Avg Close Price
Avg Yr Built
Avg Total SF
Avg Acres
# of Sales
Clackamas
$474,738
1965
1,553
0.279
256
Columbia
$457,108
1983
1,774
0.617
58
Mult.
$459,909
1951
1,591
0.163
666
Wash.
$488,954
1976
1,495
0.154
323
Yamhill
$453,522
1981
1,532
0.197
113
Grand Total
$468,595
1963
1,565
0.203
1,418
Data: RMLS | Portland Appraisal Blog
Multnomah County drives nearly half the volume, delivering the oldest average build year (1951). Washington County posts the highest average prices and hosts the most new construction. Outer counties like Columbia and Yamhill provide newer homes on larger parcels, though with far fewer transactions.
Surprisingly, across the region, starter homes are very similar in average price. The standard numerical metrics which are easy to see in RMLS, (e.g. total square footage, lot size, year built, etc.), are not the primary determinant of value. As we shall see, what matters more is quality, condition, and overall site & functional utility. Buyers in the starter home tier make conscious trade-offs between older homes with larger lots and newer homes with little to no functional backyard.
Of all the standard numeric metrics, total square footage shows one of the stronger relationships with price in the starter tier—though the influence is still modest.
Close Price vs. Total Square Feet for Starter-Tier Detached Homes ≤ 0.5 Acres (Q3 2025 RMLS data – 1,380 observations). Note: The Y-axis begins at $350,000 to allow for better viewing of the dataset.
Larger homes tend to sell for higher prices, though with considerable variation—most sales fall between 1,200 and 2,000 square feet. The very slight tilt to the right indicates a weak but present relationship between starter home size and close price. The coefficient of determination (R2) for this graph is 0.1253, meaning total square footage explains only about 12.5% of the variation in price. Since total square footage is often one of the primary determinants of value in the broader housing market, this is a big clue that the size of the home isn’t the primary factor for buyers looking to enter the starter home market.
The Historical Supply Pattern: Lot Size and Build Era
Portland’s entry-level inventory bears the clear imprint of the post-war building boom.
Lot Size vs. Year Built for Starter-Tier Detached Homes ≤ 0.5 Acres (Q3 2025 RMLS data – 1,380 observations).
A polynomial trendline highlights the peak lot sizes during the 1940s–1950s post-war era, followed by a steady decline that began in the early 1960s and accelerated in recent decades. The pattern reflects an era when generous lots were standard, followed by shrinking parcels as land values rose, urban growth boundaries took effect, and lot divisions became common. Buyers choosing older starter homes today typically gain significantly more outdoor space than those selecting new construction.
New Construction: A Modest but Noteworthy Presence
While new homes account for only 4.2% of starter-tier sales, their ability to reach this price range in a high-cost building environment remains impressive.
Segment
Avg Close Price
Avg Total SF
Avg Acres
# of Sales
Existing
$467,996
1,569
0.207
1,359
New
$482,387
1,479
0.107
59
Grand Total
$468,595
1,565
0.203
1,418
Data: RMLS | Portland Appraisal Blog
New homes sell for only about 3% more than existing ones despite brand-new condition, but deliver less interior space and roughly half the land.
Buying a new home in the starter tier is akin to buying a new car on a tight budget: you gain the benefits of fresh systems, modern design, and warranty peace of mind, but often in a smaller package with fewer amenities compared to a well-maintained used model from a higher trim line.
County
Avg Close Price
Avg Yr Built
Avg Total SF
Avg Acres
# of Sales
Clackamas
$489,803
2025
1,606
0.154
8
Columbia
$420,000
2025
1,458
0.130
2
Mult.
$450,820
2025
1,098
0.088
18
Wash.
$509,366
2025
1,699
0.079
25
Yamhill
$475,578
2025
1,540
0.216
6
Grand Total
$482,387
2025
1,479
0.107
59
Data: RMLS | Portland Appraisal Blog
For buyers, this creates a clear choice: a brand-new home with modern efficiency but typically on a very small lot—often with minimal or no usable yard space, especially in Multnomah and Washington counties where most new construction occurs—or an existing mid-century home that generally offers significantly more land and outdoor space, albeit with the potential challenges of older systems and layouts. This trade-off is particularly relevant for growing families or those prioritizing play areas, gardens, or privacy.
Appraisal Insights and Challenges
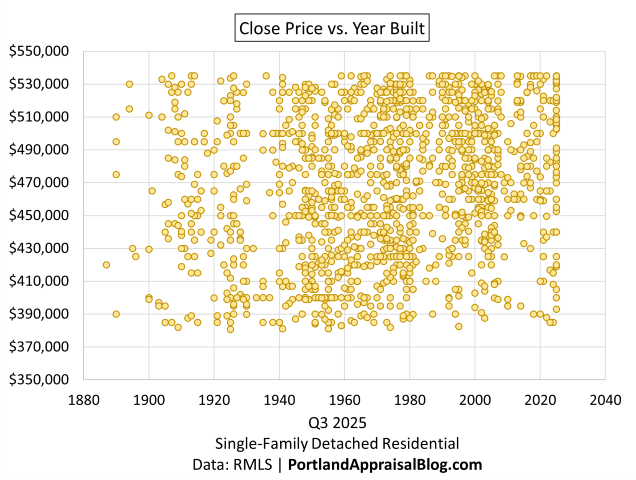
One of the most revealing patterns appears when plotting close price against build year.
Close Price vs. Year Built for Starter-Tier Detached Homes ≤ 0.5 Acres (Q3 2025 RMLS data – 1,380 observations). Note: The Y-axis begins at $350,000 to allow for better viewing of the dataset.
The remarkably consistent price band across decades illustrates that chronological age has little direct influence on value in the Portland Region’s entry-level segment.
In this tier, actual age correlates weakly with sales price because buyers weigh multiple factors:
Functional obsolescence in mid-century stock (outdated floor plans, smaller kitchens/bathrooms, less efficient systems) is often mitigated by updates and strong location appeal.
Effective age and condition drive far more of the value than the original build date.
Lot size and site utility frequently favor older homes; the smaller parcels common in new construction require substantial negative adjustments that offset much of the credit for new condition.
Comparable selection remains within county, where abundant mid-century comps in Multnomah, Clackamas, and Washington provide solid support — but thinner volume in outer counties demands careful bracketing.
When appraising a new-construction home in this tier—where truly similar recent sales are still limited and down approximately 25% year-over-year in Q3 2025 (with Multnomah County off 48%)—appraisers typically rely on other relatively recent builds (often within 10 years) and apply appropriate adjustments for differences in site characteristics, size, and location.
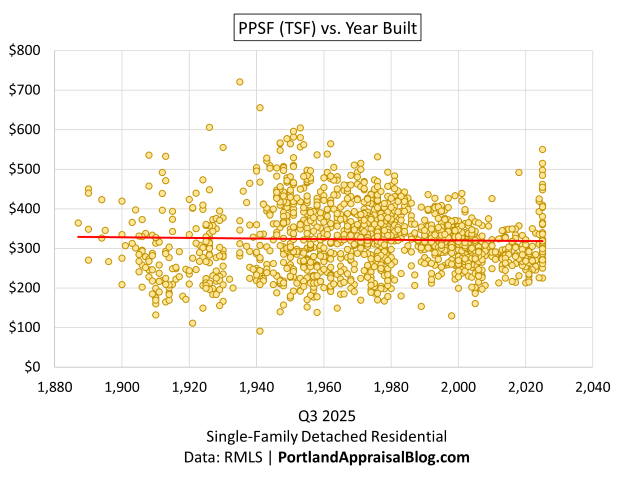
The same pattern holds when looking at the data from a price-per-square-foot lens, but with a slight twist:
PPSF (TSF) vs. Year Built for Starter-Tier Detached Homes ≤ 0.5 Acres (Q3 2025 RMLS data – 1,380 observations).
From the 1950s onward, PPSF becomes progressively more compressed—older homes exhibit wide spreads driven by dramatic differences in condition, updates, historic appeal, and location premiums, while mid-era and late-20th-century stock tightens as market expectations and remodeling homogenize perceived value.
Brand-new 2025 homes, however, break this decades-long compression pattern. Their PPSF spreads out again, reflecting greater influence from location-driven land costs and builder-specific choices (e.g., finishes, lot configuration) rather than the uniformity imposed by age and updates on existing stock. In effect, today’s entry-level new construction reintroduces variation that mirrors pre-1950 homes—but for different reasons: land value dominance and strategic specs to hit price points, rather than condition swings. This underscores why new-construction starter homes often form their own submarket. Appraisers valuing them face a narrower but distinct comp pool.
These dynamics show that the starter home market is not uniform and the appraiser needs to carefully delineate the competitive market segment to avoid having to make large adjustments between disparate properties. One technique appraisers often employ is to use similar, but older sales when recent data is thin and make an appropriate market conditions adjustment.
Conclusion
The Portland Region’s Q3 2025 starter-home segment continues to rely predominantly on mid-century inventory on lots larger than anything new we’re building today—a pattern unlikely to shift dramatically in 2026 absent major changes in new supply. (Although the City of Portland is certainly trying to incentivize new projects with SDC waivers.) The modest foothold of new construction shows builders adapting through infill and efficient design, but at the clear cost of site size and outdoor space.
For buyers, the choice boils down to priorities: modern and low-maintenance on a small lot, or more space and yard with the realities of an older home. For appraisers, lenders, and agents, recognizing how effective age, site utility, location, and condition outweigh chronological age remains key to accurate valuation in this segment.
Portland’s Temporary SDC Exemption for New Housing Units (2025–2028): Portland Appraisal Blog
Thanks for reading—I hope you found a useful insight or an unexpected nugget along the way. If you enjoyed the post, please consider subscribing for future updates.
Coda
Are you an agent in Portland who wonders why appraisers always do “x”?
A homeowner with questions about appraiser methodology?
If so, feel free to reach out—I enjoy connecting with market participants across Portland and the surrounding counties, and am always happy to help where I can.
And if you’re in need of appraisal services in Portland or anywhere in the Portland Region, we’d be glad to assist.
About the Author — Abdur Abdul‑Malik, SRA, ASA
Abdur Abdul‑Malik is the founder, author, and publisher of the Portland Appraisal Blog, where he produces original regional and neighborhood‑level housing analytics for the Portland Region. He is a certified residential appraiser serving Oregon and Washington, drawing on RMLS transaction data, public records, and custom segmentation models he has built.
He developed the Portland Appraisal Blog Affordability Index (PABAI), a payment‑based affordability metric built from actual RMLS sales. PABAI incorporates weekly updates based on the prevailing 30‑year fixed mortgage rate, providing a locally grounded measure of housing affordability across the region.
How pre-1997 Portland metro homes—especially those with veteran or active-duty exemptions—are facing sudden property tax jumps on sale or disqualification.
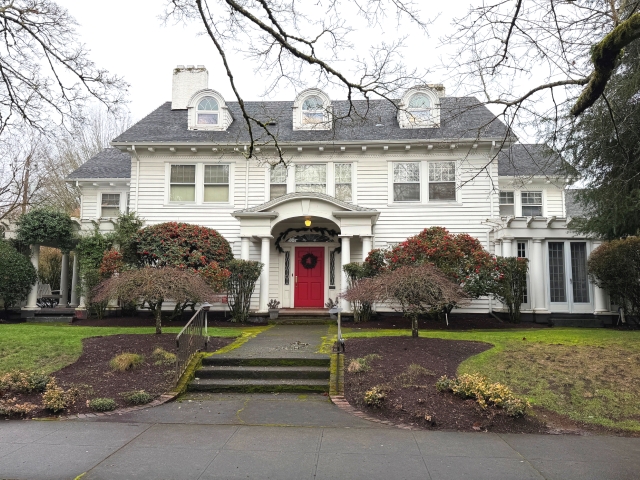
A classic pre-1940 home in the Portland Region – the type of property often benefiting from deep Measure 50 tax compression. Photo: Portland Appraisal Blog
Imagine closing on a well-maintained pre-1940 Craftsman in an established close-in Portland neighborhood. The sale price felt fair, the taxes shown on the listing and county statement appeared reasonable, and the transaction cleared due diligence without issue. Then the next year’s tax bill arrives—$2,000 to $6,000 higher than anticipated. The increase isn’t due to a sudden spike in market value, but to a change in how Oregon counties now calculate Maximum Assessed Value (MAV) when certain partial property tax exemptions end.
This situation is no longer hypothetical. Oregon REALTORS first highlighted the risk in a December 12th, 2025 internal “Forms Tip of the Week” communication, alerting members that the loss of veteran or active-duty partial exemptions—commonly triggered when a qualifying veteran or surviving spouse sells the home or passes away without a qualifying successor—can lead to significant tax increases under updated guidance from the Oregon Department of Revenue.
While the veteran and active-duty exemptions (ORS 307.250 and 307.286) have drawn attention to the issue, the underlying driver is broader: the substantial tax compression created by Measure 50 for properties built or long-held before 1997.
Historically, when these modest partial exemptions ended, counties simply removed the discount and allowed the low underlying MAV to continue. The 2024 guidance change now enforces a constitutional requirement to reset MAV closer to current market reality upon disqualification.
The outcome: buyers may face permanently higher carrying costs they did not expect, sellers (including veterans and surviving spouses) can find their properties harder to market at full value, and appraisers encounter a marketability factor worthy of note when present.
This Deep Dive reviews the mechanics, illustrates the pattern with Portland Region sales data, and provides practical steps for identifying and addressing the issue in appraisal assignments.
Understanding Measure 50: The Foundation of Tax Compression
To grasp why the loss of a veteran or active-duty exemption can now lead to significant tax increases, we must first understand Oregon’s Measure 50 property tax system, approved by voters in 1997.
Measure 50 replaced the previous tax structure with two key values for each property:
Real Market Value (RMV): The county assessor’s estimate of what the property would sell for on the open market. This value can rise or fall annually with market conditions.
Maximum Assessed Value (MAV): A separate taxable value created by Measure 50. For existing properties in 1997, MAV was initially set at approximately 90% of the 1995–1997 RMV. Thereafter, MAV is generally limited to a 3% annual increase, with exceptions for major additions, improvements, or certain other events.
The Assessed Value (AV) is the lesser of RMV or MAV. Taxes are calculated by multiplying the AV by the local tax rate.
In high-appreciation markets like the Portland metro area, this 3% cap creates substantial tax compression over time. A home purchased or built before 1997 can have an MAV far below its current RMV after decades of strong market growth.
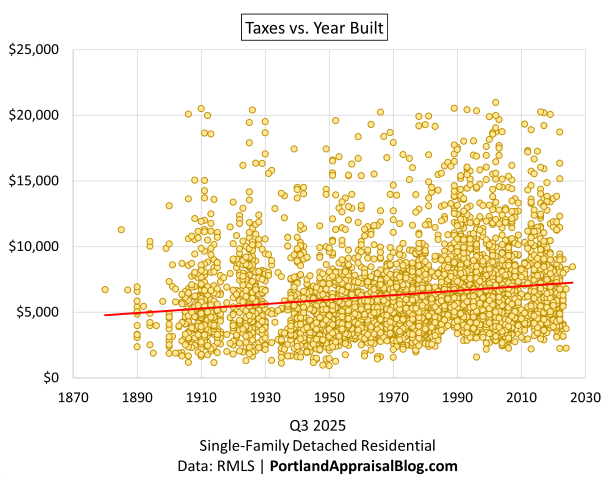
Annual property taxes vs. Year Built, excluding new construction and obvious data errors. Note: Scatter plots are limited to properties with annual taxes of $21,000 or less to highlight the primary distribution and improve readability.
The scatter illustrates the effect clearly: pre-1960 homes are overwhelmingly clustered below $10,000–$12,000 in annual taxes, with the densest grouping under $8,000–$9,000. Properties on the far left (pre-1920 builds) often show the deepest compression, having benefited from the longest period of capped MAV growth. Post-1990 homes, by contrast, display significantly higher tax burdens, reflecting less historical compression.
When a triggering event occurs—such as disqualification from a partial exemption—the MAV can be recalculated using the Changed Property Ratio (CPR), typically around 0.54 for residential properties in Portland Region counties for the 2025–2026 tax year, applied to current RMV.
In the next section, we examine local sales data that quantifies the scale of this compression and illustrates why the reset can matter in real transactions.
The Data: Tax Compression in the Portland Metro Market
Q3 2025 sales data from detached single-family residences (SFR) in the Portland Region (Clackamas, Columbia, Hood River, Multnomah, Washington, and Yamhill counties) illustrates the scale of Measure 50 compression and why a MAV reset can create material differences in carrying costs.
The table below summarizes average sale prices and annual property taxes by approximate decade built. Flagged new construction is excluded due to frequently incomplete or preliminary tax assessments at the time of sale, which can distort the pattern of long-term compression. This brings the Q3 2025 dataset to 4,256 sales total.
Decade Bucket
Avg Sale Price
Avg Annual Taxes
Avg Tax per $1k Sale Price
Pre-1940
$671,295
$6,396
$9.33
1940–1959
$607,466
$5,766
$9.53
1960–1979
$640,000
$5,783
$9.16
1980–1999
$714,535
$7,367
$10.31
2000–2019
$761,061
$7,685
$10.10
2020+ (non-new construction)
$924,420
$8,016
$9.12
Grand Total (excluding new construction)
$688,838
$6,665
$9.68
Data: RMLS | Portland Appraisal Blog
Several patterns stand out:
Absolute tax burden increases with newer construction: pre-1980 homes average $5,766–$6,396 in annual taxes, while 2000–2019 properties average $7,685 and 2020+ non-new construction reaches $8,016.
Effective burden consistency: The Tax per $1k column remains remarkably stable at ~$9–$10 across all eras. This indicates the market prices properties assuming a similar overall tax load, regardless of age.
Pre-1940 premium: Outside recent construction, pre-1940 homes command the highest average sale prices ($671,295) despite paying among the lowest absolute taxes.
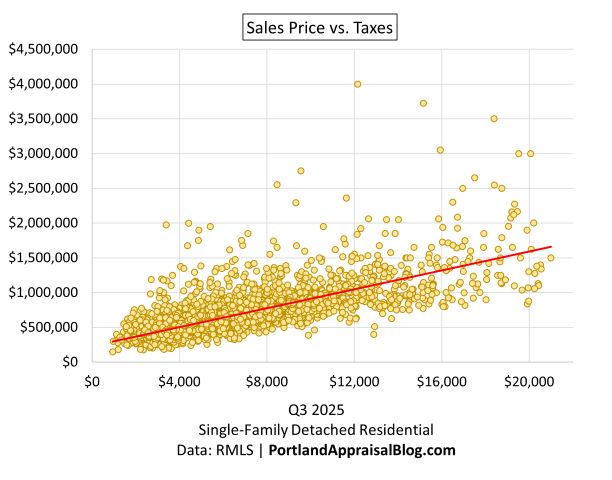
Street sign in Portland’s Historic Irvington neighborhood—one of the areas with many high-value pre-1940 homes exhibiting significant Measure 50 compression. Photo: Portland Appraisal Blog (CC BY-SA 4.0)Sale price vs. annual taxes, excluding new construction and obvious data errors. Note: Scatter plots are limited to properties with annual taxes of $21,000 or less to highlight the primary distribution and improve readability.
This scatter shows a strong positive correlation, confirming the market efficiently incorporates expected tax burden into pricing.
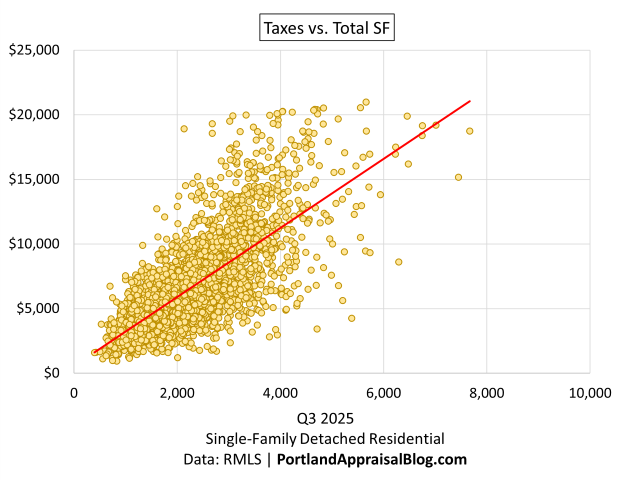
Annual taxes vs. total square footage, excluding new construction and obvious data errors. Note: Scatter plots are limited to properties with annual taxes of $21,000 or less to highlight the primary distribution and improve readability.
Here, numerous low-tax outliers are visible below the trend line—properties paying substantially less than size and location would otherwise suggest, consistent with Measure 50 compression.
Taken together, the data reveals a market that rewards older stock with lower absolute taxes without discounting sale prices accordingly. When a MAV reset occurs, absolute taxes move toward levels seen in newer comparable properties, creating the potential for noticeable increases in annual carrying costs.
In the following sections, we explore the specific veteran and active-duty exemptions and the 2024 guidance change that can trigger this alignment.
The Veteran and Active-Duty Exemptions
The exemptions at the center of the current concern are partial property tax reductions for certain military veterans, surviving spouses, and active-duty service members. With approximately 267,000 veterans living in Oregon (and over 114,000 in the Portland metro region), even a fraction of qualifying owners selling or changing status can affect a meaningful number of transactions.
The disabled veteran or surviving spouse exemption (ORS 307.250) provides a reduction to assessed value for homeowners with a service-connected disability rating of 40% or higher (or unremarried surviving spouses). For the 2025–2026 tax year, the reduction is up to $31,565 (service-connected) or $26,303 (standard), worth roughly $400–$700 in annual tax savings in Portland metro areas depending on local rates.
A separate active-duty exemption (ORS 307.286) offers a larger reduction (up to $108,366 for 2025–2026) for Oregon-domiciled service members on qualifying active duty outside the state.
Both are partial exemptions applied to the assessed value of the owner’s primary residence and tied to personal status. Eligibility generally requires a one-time application and VA certification (re-filing needed only if moving to a new property or certified by a private physician rather than the VA).
While the direct savings from these exemptions is modest ($400–$700/year for most veteran claims), the 2024 DOR guidance change treats their disqualification as triggering a full MAV reset—potentially closing decades of Measure 50 compression and leading to significantly higher taxes.
Active-duty cases (e.g., exemption ending upon return home) are less common and typically involve properties with less historical compression.
In the next section, we detail the 2024 guidance change and how it activates the reset.
The 2024 Rule Change
For decades, when a veteran or active-duty partial exemption ended, county assessors typically removed the reduction but preserved the underlying compressed MAV, allowing it to continue growing at the standard 3% rate.
This practice changed with updated guidance from the Oregon Department of Revenue, effective for disqualifications on or after January 1, 2024.
The DOR clarified that disqualification from a partial exemption triggers the constitutional requirement to recalculate MAV using the Changed Property Ratio (CPR)—the county-wide ratio of average MAV to average RMV for the property class. The new MAV becomes current RMV multiplied by the CPR (typically around 0.54 for residential properties in Portland Region counties for the 2025–2026 tax year).
This administrative enforcement of the existing constitutional language means the modest exemption savings ($400–$700/year) is no longer the only consequence. The reset can close much of the Measure 50 compression gap.
In the Portland Region data, pre-1980 homes average $5,766–$6,396 in taxes. A reset aligns absolute taxes closer to 2000+ levels ($7,685–$8,016 average), producing increases commonly in the $1,500–$4,000 annual range on typical sales, with $4,000+ possible in deeper-compression or higher-rate scenarios.
The change is statewide, though impacts vary by local appreciation and rates. Some counties have noted the potential for “significant increase” on loss of exemption.
In the next section, we examine the real-world implications for transactions and what appraisers should watch for.
Real-World Implications
The 2024 guidance change does not turn every pre-1997 home sale into a crisis, but it introduces friction that can affect negotiations, marketability, and reconciliation of comparables.
Typical tax increases fall in the $1,500–$4,000 annual range for properties in the Portland Region dataset ($600,000–$800,000 sale prices with pre-1980 build years). This translates to $125–$333 extra per month.
The Silent Car Payment
In late 2025 terms:
Average used-car payment: ~$532/month
Average new-car lease: ~$596/month
Average new-car purchase payment: ~$748/month
A $2,000–$4,000 annual increase ($167–$333/month) is less than a typical car payment but still noticeable—equivalent to a permanent, non-negotiable “utility bundle” that never goes away. For buyers already stretched in a higher-interest-rate environment, it can shift affordability and prompt renegotiation.
Outlier cases with deeper compression (often “sweet” pre-1940 homes in high-appreciation locations) can see $4,000–$8,000+ increases ($333–$667/month)—territory overlapping average used-car or new-lease payments. These are the transactions Oregon REALTORS described as producing “increases in the thousands,” sometimes requiring substantial seller concessions or risking fallout during due diligence.
The primary impact is often on marketability rather than outright deal death:
Savvy buyers (or their agents/lenders) anticipate the higher future taxes and adjust offers downward.
Sellers—particularly veterans or surviving spouses downsizing—may receive lower net proceeds (capitalizing a $3,000 increase at 6% equates to ~$50,000 less effective value).
Listings can linger if the low current taxes mask the post-closing reality.
For appraisers, this creates a new lens for outliers:
A comparable with an unexplained lower price, large concession, or extended days on market may reflect buyer reaction to a pending MAV reset.
Low-tax outliers in the grid (visible in the Taxes vs. Total SF scatter) could indicate compressed MAV or an active exemption—worth verifying via county records when material.
The change is statewide, but effects are most pronounced in areas with strong historical appreciation, like the Portland Region.
In the next section, we outline practical steps appraisers can take to identify and address this factor in reports.
What Appraisers Should Do
The 2024 guidance change introduces a marketability factor that appraisers in Oregon should consider when the subject or comparables involve pre-1997 properties, particularly those with potential veteran or active-duty exemptions.
Practical Checklist
Verify Exemption Status Review county tax records and the preliminary title report (if available) for indications of an active veteran, surviving spouse, or active-duty partial exemption. Many counties list it on the property tax statement or online portal.
Estimate Post-Transfer Tax Liability If an exemption is present and likely to disqualify on transfer (e.g., sale to non-qualifying buyer), note the potential increase. Use county assessor tools or CPR data to project the reset MAV (current RMV × CPR) and resulting taxes. Typical jumps in the Portland Region fall in the $1,500–$4,000 annual range, with higher amounts possible in deep-compression cases. Note that tax rates vary by code area.
Comment on Marketability When Material Include commentary if the differential is significant: “The subject property currently benefits from a veteran partial exemption expected to end upon transfer, potentially increasing annual taxes by an estimated $X. This may affect buyer affordability and market reaction.”
Reconcile Outliers with This Lens Low-tax outliers in the sales grid (visible in Taxes vs. Total SF analysis) may reflect compressed MAV or an active exemption—a “decaying asset” under the new guidance. Check effective tax rate (annual taxes ÷ sale price): ~0.6–0.8% may indicate compression; consider post-reset alignment (~1.1–1.3%) in reconciliation. Using a compressed comparable without adjustment risks overvaluing the subject’s marketability, as savvy buyers increasingly factor in the reset.
Use Dual Scenarios if Appropriate For subjects with active exemptions, provide current and projected post-reset tax estimates in the addendum or comments to inform the intended user.
Resources:
County assessor websites (tax statements often flag exemptions)
DOR Veteran Exemptions page
MAV Manual for general mechanics
As resets propagate into closed sales (expected more visibly in 2026 onward), this factor may explain otherwise puzzling comparables. Early identification helps ensure accurate valuation and informed clients.
In the closing section, we look at the broader outlook.
Closing Thoughts
The 2024 DOR guidance change is an administrative enforcement of a long-standing constitutional provision, but its impact is only now becoming visible as disqualifications occur and 2025–2026 tax statements arrive. Larger effects are expected in the 2026–2027 cycle as more veteran-owned properties sell or change status.
The 2025 Oregon Legislative Session saw bills (e.g., HB 2361/SB 387 aiming to lower the disability threshold, HB 3287 to increase exemption amounts) intended to expand veteran benefits. While these efforts highlight recognition of the issue, none addressed the MAV reset trigger itself. The constitutional requirement remains unless amended or re-interpreted.
For appraisers working in the Portland Region and similar appreciation-driven markets, this issue adds one more layer to marketability analysis. Low-tax outliers in older properties represent a benefit that can evaporate on transfer—reliable today, but potentially “decaying” tomorrow.
Awareness helps everyone involved: appraisers reconcile comparables more accurately, agents counsel clients proactively, and buyers/sellers avoid surprises.
If you encounter real-world examples (anonymized comps with concessions due to reset concerns, or listings noting the risk), please share them for future updates. Documenting patterns strengthens our collective understanding.
Thank you for reading this Appraisal Deep Dive. Stay informed and precise in your work.
Quick Reference Cheat Sheet
Reset Formula
Real Market Value (RMV) × Changed Property Ratio (CPR)
Typical CPR (2025–2026, Portland Region residential)
~0.54 (updated annually each October)
Reset Trigger
Disqualification from veteran/active-duty exemption
Thanks for reading—I hope you found a useful insight or an unexpected nugget along the way. If you enjoyed the post, please consider subscribing for future updates.
Coda
Are you an agent in Portland who wonders why appraisers always do “x”?
A homeowner with questions about appraiser methodology?
If so, feel free to reach out—I enjoy connecting with market participants across Portland and the surrounding counties, and am always happy to help where I can.
And if you’re in need of appraisal services in Portland or anywhere in the Portland Region, we’d be glad to assist.
About the Author — Abdur Abdul‑Malik, SRA, ASA
Abdur Abdul‑Malik is the founder, author, and publisher of the Portland Appraisal Blog, where he produces original regional and neighborhood‑level housing analytics for the Portland Region. He is a certified residential appraiser serving Oregon and Washington, drawing on RMLS transaction data, public records, and custom segmentation models he has built.
He developed the Portland Appraisal Blog Affordability Index (PABAI), a payment‑based affordability metric built from actual RMLS sales. PABAI incorporates weekly updates based on the prevailing 30‑year fixed mortgage rate, providing a locally grounded measure of housing affordability across the region.