Detached-home sales in Troutdale were highly concentrated, with 79.57% of all sales occurring between 1,200 SF and 2,099 SF during 2024-2025. Average home size declined by 62 SF, while median home size fell by 113 SF.
Troutdale city seal—”Gateway to the Gorge.” Photo: Abdur Abdul-Malik, Portland Appraisal Blog
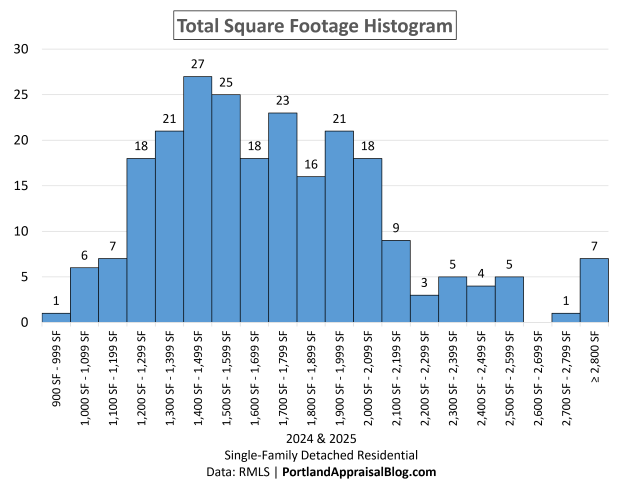
Detached-home sales in Troutdale spanned a wide range of sizes during 2024 and 2025. While sales ranged from under 1,000 square feet to more than 5,000 square feet, most buyers purchased homes within a much narrower range, with homes 1,400-1,499 SF the most dominant bracket.
The table below compares key home-size metrics across both years.
Category
2024
2025
Change
Average Total SF
1,768
1,706
-62 SF
Median Total SF
1,727
1,614
-113 SF
Smallest Sale
1,089
980
-109 SF
Largest Sale
2,992
5,100
+2,108 SF
Total # of Sales
112
123
+11 homes
City of Troutdale Total Square Footage Comparisons Single-Family Detached Residential | 2024 vs. 2025 Data: RMLS |PortlandAppraisalBlog.com
Smaller detached homes sold on average in 2025 than in 2024. Average home size declined from 1,768 SF to 1,706 SF, while median size fell from 1,727 SF to 1,614 SF. At the same time, the largest detached-home sale increased from 2,992 SF to 5,100 SF, illustrating the presence of a small upper-end market.
The chart below shows where detached-home sales were concentrated by total square footage during 2024 and 2025.
Detached homes smaller than 1,200 SF saw relatively few transactions. The number of sales increased noticeably beginning in the 1,200-1,299 SF & 1,300-1,399 ranges and remained strong through much of the market’s mid-sized ranges, reaching a peak in the 1,400-1,499 SF range, which recorded 27 sales. Other notable concentrations occurred in the 1,500-1,599 SF range (25 sales), the 1,700-1,799 SF range (23 sales), and the 1,900-1,999 SF range (21 sales).
The final size band (≥2,800 SF) serves as a catch-all category for the market’s thin upper tail. Larger detached homes continued to sell throughout the study period, but transaction volume declined substantially beyond roughly 2,100 SF.
The table below summarizes each size band and includes average sale price, average living area, average year built, and average lot size.
SF Range
Sales
Avg Close Price
Avg Total SF
Avg Year Built
Avg Acres
900 SF – 999 SF
1
$422,500
980
1979
0.130
1,000 SF – 1,099 SF
6
$424,167
1,074
1981
0.228
1,100 SF – 1,199 SF
7
$451,286
1,146
1979
0.166
1,200 SF – 1,299 SF
18
$457,244
1,251
1980
0.181
1,300 SF – 1,399 SF
21
$467,995
1,351
1984
0.198
1,400 SF – 1,499 SF
27
$481,009
1,443
1986
0.319
1,500 SF – 1,599 SF
25
$473,312
1,555
1989
0.172
1,600 SF – 1,699 SF
18
$485,436
1,641
1990
0.181
1,700 SF – 1,799 SF
23
$479,465
1,752
1988
0.177
1,800 SF – 1,899 SF
16
$516,053
1,851
1991
0.235
1,900 SF – 1,999 SF
21
$530,940
1,947
1994
0.188
2,000 SF – 2,099 SF
18
$530,242
2,042
1994
0.188
2,100 SF – 2,199 SF
9
$536,222
2,156
1997
0.143
2,200 SF – 2,299 SF
3
$559,300
2,240
1985
0.233
2,300 SF – 2,399 SF
5
$582,600
2,333
2002
0.154
2,400 SF – 2,499 SF
4
$568,750
2,434
2001
0.160
2,500 SF – 2,599 SF
5
$560,780
2,541
1997
0.164
2,600 SF – 2,699 SF
0
—
—
—
—
2,700 SF – 2,799 SF
1
$705,000
2,778
1990
0.620
≥ 2,800 SF
7
$743,412
3,367
1986
0.580
Total/Avg
235
$502,664
1,735
1989
0.214
City of Troutdale Home Sales by Size Band Single-Family Detached Residential | 2024 & 2025 Data: RMLS |PortlandAppraisalBlog.com
The market was highly concentrated. Homes between 1,200 SF and 2,099 SF accounted for 187 of 235 sales, or 79.57% of all detached-home transactions during the study period.
Within this range, average sale prices increased from approximately $457,000 to a little over $530,000 as home size increased. Most homes in the market’s most active size ranges were built during the 1980s and 1990s, reflecting the era that helped define much of Troutdale’s detached-housing stock.
Despite substantial differences in living area, average lot sizes remained relatively consistent throughout much of the market’s core size ranges.
Troutdale’s detached-home market was highly concentrated between 1,200 SF and 2,099 SF.
PAB Insights is a Portland Appraisal Blog (PAB) series providing concise, data-driven answers to individual housing-market questions using transaction-level research, local market knowledge, and proprietary models, such as the Portland Appraisal Blog Affordability Index (PABAI).
Sources & Further Reading
All data presented in this PAB Insight is sourced directly from RMLS and has been subjected to our rigorous cleaning and validation process to ensure reliability for detached single-family residential analysis in the six-county Portland Region. The trends, comparisons, and commentary are the result of original appraisal expertise and independent analysis—not aggregated from secondary sources or news summaries.
PAB Insights: What Could Different Household Incomes Buy Among Troutdale’s Affordable Homes?: Portland Appraisal Blog
PAB Insights: What Income Was Required to Buy a Home in Troutdale (2024-2025)?: Portland Appraisal Blog
Coda
Thanks for reading—I hope you found a useful insight or an unexpected nugget along the way. If you enjoyed the post, please consider subscribing for future updates.
Are you an agent in Portland who wonders why appraisers always do “x”?
A homeowner with questions about appraiser methodology?
If so, feel free to reach out—I enjoy connecting with market participants across Portland and the surrounding counties, and am always happy to help where I can.
And if you’re in need of appraisal services in Troutdale or anywhere in the Portland Region, we’d be glad to assist.
About the Author — Abdur Abdul‑Malik, SRA, ASA
Abdur Abdul‑Malik is the founder, author, and publisher of the Portland Appraisal Blog, where he produces original regional and neighborhood‑level housing analytics for the Portland Region. He is a certified residential appraiser serving Oregon and Washington, drawing on RMLS transaction data, public records, and custom segmentation models he has built.
He developed the Portland Appraisal Blog Affordability Index (PABAI), a payment‑based affordability metric built from actual RMLS sales. PABAI incorporates weekly updates based on the prevailing 30‑year fixed mortgage rate, providing a locally grounded measure of housing affordability across the region.
Average required income for Troutdale detached homes declined from $137,475 in 2024 to $131,873 in 2025. While required incomes fell only modestly, affordable detached-home sales increased dramatically as many homes sat near the affordability threshold. Rates tipped the scale.
Troutdale arch sign. Photo: Abdur Abdul-Malik, Portland Appraisal Blog
The amount of income required to purchase a detached home in Troutdale declined modestly between 2024 and 2025. While average and median required incomes fell by roughly 4%, the share of detached-home sales classified as affordable under the Portland Appraisal Blog Affordability Index (PABAI) increased dramatically.
The table below compares key required-income metrics across both years.
Metric
2024
2025
Change
Avg Required Income
$137,475
$131,873
-4.07%
Median Required Income
$134,148
$128,256
-4.39%
Affordable Sales
7
43
+36 homes
% Affordable
6.25%
34.96%
+28.71 pts
Detached-home affordability overview, Troutdale city limits. Affordable homes determined using PABAI. Single-Family Detached Residential | 2024 vs. 2025 Data: RMLS |PortlandAppraisalBlog.com
How “affordable” is defined: PABAI calculates the income needed to buy each home using its actual reported price, taxes, HOA dues, and insurance estimate, financed at the Freddie Mac 30-year rate in effect at the time of sale. A home counts as affordable if that required income is at or below the HUD median family income for the Portland-Vancouver-Hillsboro MSA in effect at the time.
At first glance, the affordability gains appear out of proportion to the decline in required incomes. Average required income fell just 4.07%, yet affordable detached-home sales increased from 7 to 43.
Part of the explanation can be found in how ownership costs were allocated.
Category
2024
2025
Change
Avg Principal & Interest Share
82.47%
82.05%
-0.42 pts
Avg Taxes Share
12.01%
12.17%
+0.16 pts
Avg HOA Share
0.21%
0.41%
+0.20 pts
Avg Insurance Share
5.31%
5.37%
+0.06 pts
Average share of housing payments attributable to principal & interest, property taxes, HOA dues, and insurance as modeled under the PABAI framework. Shares are averaged across all detached sales; sales without HOA dues count as 0% HOA. Single-Family Detached Residential | 2024 vs. 2025 Data: RMLS |PortlandAppraisalBlog.com
Mortgage principal and interest accounted for roughly 82% of the typical modeled housing payment in both years. While the P&I share declined by only 0.42 percentage points between 2024 and 2025, that small change proved meaningful because detached-home sales were heavily concentrated near the affordability threshold. In a market sitting at the boundary of affordability, even modest improvements in financing costs can move a significant number of homes from unaffordable to affordable.
Taxes and insurance remained relatively stable. HOA dues represented a larger share of modeled ownership costs in 2025, although part of that increase can be attributed to a greater number of HOA-governed homes selling in 2025 (35) than in 2024 (24).
The table above illustrates why mortgage rates matter. When more than four-fifths of a typical housing payment is attributable to financing costs, even modest improvements in mortgage financing conditions can materially affect affordability.
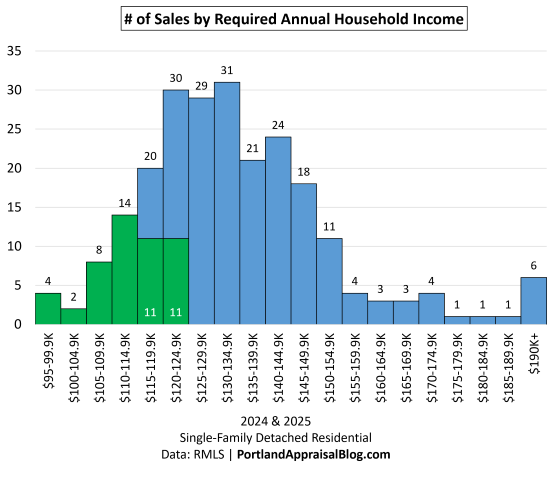
The chart below combines 2024 and 2025 detached-home sales to show where required incomes were concentrated.
Most detached-home sales required between roughly $115,000 and $149,999 of annual household income. The green bars represent homes that met the PABAI affordability standard in effect at the time of sale.
The first four income bands were naturally affordable because they generally fell below the applicable HUD median family income thresholds throughout the study period. Additional affordable sales appeared in the $115,000-$119,999 and $120,000-$124,999 income bands, reflecting changes in affordability thresholds and financing conditions over time.
The table below summarizes the distribution and includes the percentage of sales in each band, making it easier to evaluate where the market was concentrated.
Required Income
# of Sales
% of Sales
# Affordable
$95-99.9K
4
1.70%
4
$100-104.9K
2
0.85%
2
$105-109.9K
8
3.40%
8
$110-114.9K
14
5.96%
14
$115-119.9K
20
8.51%
11
$120-124.9K
30
12.77%
11
$125-129.9K
29
12.34%
0
$130-134.9K
31
13.19%
0
$135-139.9K
21
8.94%
0
$140-144.9K
24
10.21%
0
$145-149.9K
18
7.66%
0
$150-154.9K
11
4.68%
0
$155-159.9K
4
1.70%
0
$160-164.9K
3
1.28%
0
$165-169.9K
3
1.28%
0
$170-174.9K
4
1.70%
0
$175-179.9K
1
0.43%
0
$180-184.9K
1
0.43%
0
$185-189.9K
1
0.43%
0
$190K+
6
2.55%
0
Sum
235
100.00%
50
Detached-home sales by required income band (2024-2025), including the share of sales and number classified as affordable under PABAI. Lower bound inclusive. Single-Family Detached Residential | 2024 & 2025 Data: RMLS |PortlandAppraisalBlog.com
Nearly three-quarters (73.62%) of all detached-home sales required between $115,000 to $149,999 of annual household income. The single largest income band was $130,000 to $134,999, accounting for 13.19% of all sales.
The market was not dominated by homes requiring substantially more income than the affordability threshold. Instead, many sales clustered immediately around it. As mortgage rates modestly improved during much of the 2025 selling season, required incomes fell enough to bring more homes into the affordability zone. Affordability was also buoyed by a rising HUD median family income for the Portland-Vancouver-Hillsboro MSA: $114,400 in 2024, rising to $124,100 by April 2025 and holding there through year-end.
PAB Insights is a Portland Appraisal Blog (PAB) series providing concise, data-driven answers to individual housing-market questions using transaction-level research, local market knowledge, and proprietary models, such as the Portland Appraisal Blog Affordability Index (PABAI).
Sources & Further Reading
All data presented in this PAB Insight is sourced directly from RMLS and has been subjected to our rigorous cleaning and validation process to ensure reliability for detached single-family residential analysis in the six-county Portland Region. The trends, comparisons, and commentary are the result of original appraisal expertise and independent analysis—not aggregated from secondary sources or news summaries.
PAB Insights: What Could Different Household Incomes Buy Among Troutdale’s Affordable Homes?: Portland Appraisal Blog
Coda
Thanks for reading—I hope you found a useful insight or an unexpected nugget along the way. If you enjoyed the post, please consider subscribing for future updates.
Are you an agent in Portland who wonders why appraisers always do “x”?
A homeowner with questions about appraiser methodology?
If so, feel free to reach out—I enjoy connecting with market participants across Portland and the surrounding counties, and am always happy to help where I can.
And if you’re in need of appraisal services in Troutdale or anywhere in the Portland Region, we’d be glad to assist.
About the Author — Abdur Abdul‑Malik, SRA, ASA
Abdur Abdul‑Malik is the founder, author, and publisher of the Portland Appraisal Blog, where he produces original regional and neighborhood‑level housing analytics for the Portland Region. He is a certified residential appraiser serving Oregon and Washington, drawing on RMLS transaction data, public records, and custom segmentation models he has built.
He developed the Portland Appraisal Blog Affordability Index (PABAI), a payment‑based affordability metric built from actual RMLS sales. PABAI incorporates weekly updates based on the prevailing 30‑year fixed mortgage rate, providing a locally grounded measure of housing affordability across the region.
During 2024 and 2025, 50 detached homes in the City of Troutdale were classified as affordable, as measured by the Portland Appraisal Blog Affordability Index (PABAI). A household earning approximately $124,000 could have qualified for all of them.
Troutdale city seal—”Gateway to the Gorge.” Photo: Abdur Abdul-Malik, Portland Appraisal Blog
During 2024 and 2025, detached homes accounted for 92.16% of all residential sales occurring within Troutdale city limits. As a result, most discussions about housing affordability in Troutdale are effectively discussions about the detached-home market.
During the two-year study period, 235 detached homes sold on the open market. Of those, 50 (21.28%) were classified as affordable under the Portland Appraisal Blog Affordability Index (PABAI). The majority of the affordable homes (43 of the 50) sold in 2025.
Metric
Value
Total Detached Sales
235
Affordable Detached Sales
50
% Affordable
21.28%
Min Required Income (All Detached Sales)
$95,373
Median Required Income (All Detached Sales)
$131,883
Max Required Income (All Detached Sales)
$242,349
Detached-home affordability overview, Troutdale city limits. Affordable homes determined using PABAI. Single-Family Detached Residential | 2024 & 2025 Data: RMLS |PortlandAppraisalBlog.com
How “affordable” is defined: PABAI calculates the income needed to buy each home using its actual reported price, taxes, HOA dues, and insurance estimate, financed at the Freddie Mac 30-year rate in effect at the time of sale. A home counts as affordable if that required income is at or below the HUD median family income for the Portland-Vancouver-Hillsboro MSA in effect at the time.
The required-income figures above describe the entire detached-home market, not just affordable homes. During the study period, the most expensive detached home that still qualified as affordable required approximately $123,916 of household income. That figure closely aligned with the applicable HUD MSA family income used during much of the period.
The following table is cumulative. For example, a household earning $115,000 could theoretically access all affordable detached homes requiring $115,000 or less in qualifying income. Likewise, a household earning $124,000 could access the entire inventory of detached homes meeting the affordability standard.
Household Income
# Affordable
Avg Price
Avg Total SF
Avg Acres
Avg Year
$100,000
4
$359,375
1,495
0.175
1956
$115,000
28
$410,250
1,425
0.162
1981
$124,000
50
$428,457
1,462
0.164
1984
Average characteristics of cumulative affordable detached-home inventory accessible at selected household income levels. Data: RMLS | PortlandAppraisalBlog.com
One of the most interesting findings is that higher household income primarily expanded buyer choice rather than dramatically changing the type of home available. The number of attainable homes increased substantially as income increased, but the physical characteristics of those homes remained surprisingly similar.
Home size, lot size, and age varied less than many buyers might expect. Across all three tiers, the typical affordable detached home remained roughly 1,400 to 1,500 square feet on approximately 0.16 to 0.18 acres.
The more meaningful differences appeared in inventory count and property condition. The lowest-income tier included several fixer and distressed-sale opportunities, while the highest-income tier opened access to a much larger selection of well-maintained and updated homes. The affordable inventory was dominated by traditional suburban housing styles, particularly one-story ranch homes and split-level designs. Among the ten highest-priced affordable detached homes sold during the study period, only one was reported in below-average condition, with the remainder described as being in good, updated, or remodeled condition.
For Troutdale’s relatively uniform detached-home market, additional household income often translated into more options and better-condition homes rather than dramatically larger ones. Households near the $124,000 income tier not only gained access to the full affordable detached-home inventory, but also enjoyed a broader selection of turnkey homes requiring little or no immediate repair work.
About PAB Insights
PAB Insights is a Portland Appraisal Blog (PAB) series providing concise, data-driven answers to individual housing-market questions using transaction-level research, local market knowledge, and proprietary models, such as the Portland Appraisal Blog Affordability Index (PABAI).
Sources & Further Reading
All data presented in this PAB Insight is sourced directly from RMLS and has been subjected to our rigorous cleaning and validation process to ensure reliability for detached single-family residential analysis in the six-county Portland Region. The trends, comparisons, and commentary are the result of original appraisal expertise and independent analysis—not aggregated from secondary sources or news summaries.
Thanks for reading—I hope you found a useful insight or an unexpected nugget along the way. If you enjoyed the post, please consider subscribing for future updates.
Are you an agent in Portland who wonders why appraisers always do “x”?
A homeowner with questions about appraiser methodology?
If so, feel free to reach out—I enjoy connecting with market participants across Portland and the surrounding counties, and am always happy to help where I can.
And if you’re in need of appraisal services in Troutdale or anywhere in the Portland Region, we’d be glad to assist.
About the Author — Abdur Abdul‑Malik, SRA, ASA
Abdur Abdul‑Malik is the founder, author, and publisher of the Portland Appraisal Blog, where he produces original regional and neighborhood‑level housing analytics for the Portland Region. He is a certified residential appraiser serving Oregon and Washington, drawing on RMLS transaction data, public records, and custom segmentation models he has built.
He developed the Portland Appraisal Blog Affordability Index (PABAI), a payment‑based affordability metric built from actual RMLS sales. PABAI incorporates weekly updates based on the prevailing 30‑year fixed mortgage rate, providing a locally grounded measure of housing affordability across the region.
Troutdale’s 2025 housing market generated more than $64 million in residential sales, with detached homes accounting for over 93% of all transactions. Affordability rose sharply; 35% of detached sales were affordable, up from 6%. This was due to softer prices and more favorable mortgage interest rates during peak selling season in 2025 compared with 2024.
Troutdale’s “Gateway to the Gorge” arch welcomes visitors to the city’s historic downtown district near the western entrance to the Columbia River Gorge. Photo: Abdur Abdul-Malik, Portland Appraisal Blog
About This Snapshot
This snapshot summarizes residential sales occurring within the official City of Troutdale limits during calendar year 2025 (with some comparisons to calendar year 2024). Included property types are detached homes, attached homes, condominiums, and manufactured homes on owned land. Data are sourced from RMLS and have undergone our standard cleaning and validation process. Manufactured homes located in leased-space parks are not included. For additional information regarding data cleaning procedures and common MLS data challenges, see the dedicated page: RMLS Data Accuracy Challenges.
Tables in this snapshot cover important metrics such as:
Sales price to original list price: SP/OLP
Price per square foot (total square footage): PPSF (TSF)
Cumulative days on market: CDOM
Average lot size in acres: ac
Market Overview
Located in eastern Multnomah County, Troutdale is a community in the Portland Region best known as the “Gateway to the Gorge.” Situated near the western entrance to the Columbia River Gorge, the city offers convenient access to outdoor recreation while remaining connected to the broader Portland metropolitan area.
Citywide Residential Market Snapshot
The following table summarizes residential sales occurring within Troutdale city limits during calendar year 2025. Included property types are detached homes, attached homes, condominiums, and manufactured homes on owned land. Together, these four segments provide a high-level overview of Troutdale’s owner-occupied residential market.
Category
Detached
Attached
Condo
Manuf.
Total Dollar Volume
$60,926,158
$2,652,800
$665,000
$0
Average Price
$495,335
$378,971
$332,500
—
Average PPSF (Total SF)
$302.51
$250.99
$226.84
—
Average Total SF
1,706
1,530
1,467
—
Average Lot Size (ac)
0.2160
0.0614
N/A
—
Average Age (Yrs)
37.38
17.00
21.50
—
Average CDOM
42.25
92.14
73.50
—
Total # of Sales
123
7
2
0
% of Market
93.18%
5.30%
1.52%
0.00%
Highest Sale
$840,000
$440,000
$350,000
—
Lowest Sale
$360,000
$332,800
$315,000
—
# Affordable
43
6
2
—
% Affordable
34.96%
85.71%
100.00%
—
January 2025 – December 2025 (132 total residential sales). Data: RMLS | PortlandAppraisalBlog.com
Detached homes accounted for the overwhelming majority of residential sales activity in Troutdale during 2025. Total residential dollar volume across all tracked housing segments reached approximately $64.2 million, with detached homes representing more than 93% of all sales and nearly 95% of total dollar volume. Attached homes and condominiums represented a relatively small share of the market, while no manufactured homes on owned land sold during the year. The following sections examine each segment in greater detail.
Detached Homes
Detached homes represent the largest and most active residential housing segment in Troutdale. Because detached properties accounted for more than 9 out of 10 sales during 2025, this segment provides the clearest view of local market conditions.
Detached Homes Market Statistics
The following table compares detached-home sales activity occurring within Troutdale city limits during 2024 and 2025. Metrics include sales volume, pricing, property characteristics, marketing times, and affordability.
Category
2024
2025
Change
Total $ Volume
$57,199,850
$60,926,158
+6.51%
Average Price
$510,713
$495,335
-3.01%
Median Price
$501,500
$479,000
-4.49%
Avg SP/OLP
99.27%
98.09%
-1.19 pts
Avg PPSF (TSF)
$298.54
$302.51
+1.33%
Avg HOA Dues
$30.80
$44.72
+45.20%
Avg Total SF
1,768
1,706
-3.52%
Avg Lot Size (ac)
0.2160
0.2121
-1.77%
Avg Age (Yrs)
35.32
37.38
+5.83%
Avg CDOM
39.07
42.25
+8.14%
Total # of Sales
112
123
+9.82%
# of New Constr.
0
0
—
# Affordable
7
43
+36 homes
% Affordable
6.25%
34.96%
+28.71 pts
Note: The calculated average HOA dues is for sales reporting nonzero HOA dues (24 sales for 2024 & 35 sales for 2025). All other metrics use the full dataset for each year. Single-Family Detached Residential | 2024 & 2025 Data: RMLS | PortlandAppraisalBlog.com
Detached-home sales activity increased during 2025, with total sales rising from 112 to 123 and total dollar volume increasing 6.51% to approximately $60.9 million. Despite stronger sales activity, both average and median sale prices declined modestly, while average days on market increased just 3 days, from 39 to 42 days. Buyers also gained slightly more negotiating leverage, with the average sale-to-original-list-price ratio declining from 99.27% to 98.09%.
The typical detached home sold during 2025 was somewhat smaller and slightly older than in 2024, while average price per square foot increased modestly. No new detached-home construction sales were recorded in either year, reinforcing Troutdale’s role as a largely resale-driven housing market. HOA participation remained a minority characteristic of the detached market, though the share of detached-home sales reporting HOA dues increased from approximately 21% in 2024 to 29% in 2025.
Detached Homes Sales by Price Range
The following table summarizes detached-home sales occurring within Troutdale city limits during 2025 by price range. In addition to sales volume, the table highlights the typical size and age of homes sold within each price band.
Troutdale’s detached-home market was concentrated in the middle price ranges during 2025. More than 89% of detached-home sales occurred between $400,000 and $599,999, with the $400,000-$499,999 range alone accounting for 71 of 123 sales. As sale prices increased, average home size generally increased as well, from approximately 1,500 square feet in the $400,000-$499,999 range to more than 3,200 square feet in the $700,000+ ranges.
While most sales occurred in homes built during the 1980s and 1990s, the two highest-priced detached-home sales were very different properties. One involved a nearly four-acre mixed-use development site along the Sandy River with an older home contributing little to overall value, while the other was a large historic residence with more than 5,000 square feet of living area and an accessory dwelling unit. These sales illustrate how Troutdale’s highest-priced properties can derive value from factors such as land, development potential, size, and unique property characteristics rather than age alone.
Detached Homes Affordability
The following table summarizes detached-home affordability in Troutdale during 2024 and 2025 using PABAI. In addition to the number and percentage of affordable sales, the table reports the highest affordable sale, the average sale price of affordable homes, and the average household income required to purchase those homes under prevailing market conditions at the time of sale.
Category
2024
2025
Change
Affordable Sales
7
43
+36 homes
% Affordable
6.25%
34.96%
+28.71 pts
Highest Affordable Sale
$445,000
$474,900
+6.72%
Avg Price
$409,080
$431,612
+5.51%
Avg Required Income
$108,737
$114,232
+$5,494.37
Affordable sales are determined using the Portland Appraisal Blog Affordability Index (PABAI), which evaluates each detached-home sale using prevailing mortgage rates, household income assumptions, taxes, insurance, and financing costs at the time of sale.
Detached-home affordability improved substantially during 2025. The number of affordable detached-home sales increased from 7 to 43, while the share of affordable sales increased from 6.25% to 34.96% of the market. The highest affordable detached-home sale increased from $445,000 in 2024 to $474,900 in 2025.
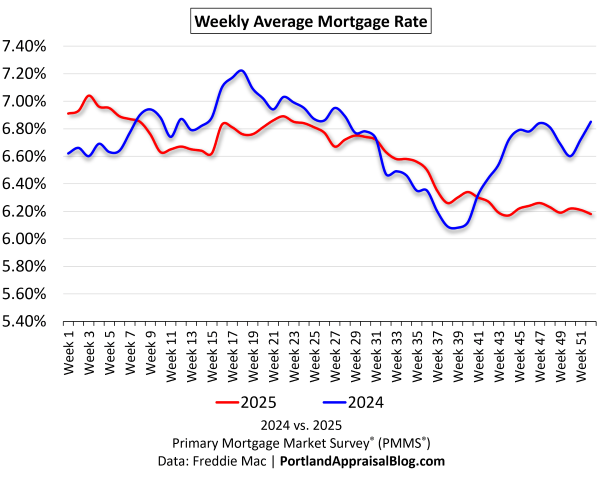
As shown above, mortgage rates were generally higher throughout much of 2024 than 2025. Combined with modest declines in detached-home prices, lower financing costs expanded the number of homes meeting the affordability standard even though the highest affordable detached-home sale changed very little.
The average affordable detached home sold for $431,612 during 2025 and required an estimated household income of approximately $114,232. While affordability remained far from universal, Troutdale offered substantially more attainable detached-home ownership opportunities in 2025 than in the prior year.
Attached Homes
Attached homes represent a small but distinct segment of Troutdale’s housing market. While sales activity is limited compared with detached homes, attached housing can provide an ownership alternative for buyers seeking lower-maintenance living or a smaller land component.
Attached Homes Market Statistics
The following table compares attached-home sales activity occurring within Troutdale city limits during 2024 and 2025. Due to the limited number of sales, the results are best viewed as descriptive measures of market activity rather than indicators of broader market trends.
Category
2024
2025
Change
Total $ Volume
$2,662,500
$2,652,800
-0.36%
Average Price
$443,750
$378,971
-14.60%
Median Price
$420,000
$390,000
-7.14%
Avg SP/OLP
96.36%
88.63%
-8.03 pts
Avg PPSF (TSF)
$289.56
$250.99
-13.32%
Avg HOA Dues
$159.00
$224.25
+41.04%
Avg Total SF
1,528
1,530
+0.19%
Avg Lot Size (ac)
0.0350
0.0614
+75.51%
Avg Age (Yrs)
6.67
17.00
+155.00%
Avg CDOM
47.50
92.14
+93.98%
Total # of Sales
6
7
+16.67%
# of New Constr.
2
0
-100.00%
# Affordable
4
6
+ 2 homes
% Affordable
66.67%
85.71%
+19.04 pts
Note: The calculated average HOA dues is for sales reporting nonzero HOA dues (1 sale for 2024 & 4 sales for 2025). All other metrics use the full dataset for each year. Single-Family Attached Residential | 2024 & 2025 Data: RMLS | PortlandAppraisalBlog.com
Attached-home sales represented a small portion of Troutdale’s residential market in both years, with only seven sales recorded during 2025. Despite the limited number of transactions, attached homes consistently contributed approximately $2.65 million in annual residential dollar volume during both 2024 and 2025.
Pricing measures, including average sale price, price per square foot, and sale-to-list-price ratio, were all lower in 2025 than in 2024. Because the attached-home market consists of a very small number of transactions, year-to-year changes are often skewed by compositional differences among the sales.
Attached Homes Affordability
The following table summarizes attached-home affordability in Troutdale during 2024 and 2025 using PABAI.
Category
2024
2025
Change
Affordable Sales
4
6
+2 homes
% Affordable
66.67%
85.71%
+19.04 pts
Highest Affordable Sale
$420,000
$405,000
-3.57%
Avg Price
$406,250
$368,800
-9.22%
Avg Required Income
$111,482
$104,015
-$7,466.98
Affordable sales are determined using the Portland Appraisal Blog Affordability Index (PABAI), which evaluates each attached-home sale using prevailing mortgage rates, household income assumptions, taxes, insurance, and financing costs at the time of sale.
Attached homes remained one of Troutdale’s most affordable ownership options during both years analyzed. Six of seven attached-home sales met the PABAI affordability standard during 2025, compared with four of six sales during 2024. The average required household income fell from approximately $111,000 to $104,000; largely due to lower average sales prices in 2025 compared to the previous year.
Because the attached-home market consists of only a handful of transactions each year, affordability results should be interpreted cautiously. Nevertheless, the segment consistently provided ownership opportunities at lower price points than the detached-home market, with a large majority of sales meeting the affordability standard in both years.
Condominiums
Condominiums represent a very small segment of Troutdale’s residential market. Like attached homes, due to the limited number of sales, the results are best viewed as descriptive measures of market activity rather than indicators of broader market trends.
Condominium Housing Market Statistics
The following table compares condominium sales activity occurring within Troutdale city limits during 2024 and 2025.
Category
2024
2025
Change
Total $ Volume
$1,804,900
$665,000
-63.16%
Average Price
$360,980
$332,500
-7.89%
Median Price
$347,000
$332,500
-4.18%
Avg SP/OLP
95.68%
95.65%
-0.03 pts
Avg PPSF (TSF)
$223.12
$226.84
+1.67%
Avg HOA Dues
$357.60
$415.00
+16.05%
Avg Total SF
1,634
1,467
-10.20%
Avg Age (Yrs)
21.80
21.50
-1.38%
Avg CDOM
55.20
73.50
+33.15%
Total # of Sales
5
2
-60.00%
# of New Constr.
0
0
—
# Affordable
4
2
-2 homes
% Affordable
80.00%
100.00%
+20.00 pts
Note: All metrics use the full dataset for each year (including HOA dues). Condominium Residential | 2024 & 2025 Data: RMLS | PortlandAppraisalBlog.com
Condominium sales activity remained limited during both years, with only five sales recorded in 2024 and two sales recorded in 2025. While Troutdale contains several condominium communities, recent sales activity was concentrated in a small number of developments. Most of the condominium sales occurring during the period analyzed were located within the Edgefield Meadows community, a townhome-style condominium development.
Pricing remained relatively stable despite the limited number of transactions. Average price per square foot changed very little between years. All condominium sales reported HOA dues, with average monthly dues increasing from approximately $358 to $415. Because the condominium market consists of only a handful of transactions each year, changes in individual metrics strongly reflect the mix of unit sales.
Condominium Housing Affordability
The following table summarizes condominium affordability in Troutdale during 2024 and 2025 using PABAI.
Category
2024
2025
Change
Affordable Sales
4
2
-2 homes
% Affordable
80.00%
100.00%
+20.00 pts
Highest Affordable Sale
$394,000
$350,000
-11.17%
Avg Price
$346,225
$332,500
-3.96%
Avg Required Income
$106,279
$107,724
+$1,445.28
Affordable sales are determined using the Portland Appraisal Blog Affordability Index (PABAI), which evaluates each condominium sale using prevailing mortgage rates, household income assumptions, taxes, insurance, and financing costs at the time of sale.
Condominium affordability remained strong during both years analyzed. Four of five condominium sales met the PABAI affordability standard during 2024, while both condominium sales recorded during 2025 qualified as affordable. Average affordable sale prices remained in the mid-$300,000 range, while the average required household income remained relatively stable near $106,000 to $108,000.
Because condominium activity in Troutdale is limited, affordability results are heavily influenced by the specific units that sell during a given year. Nevertheless, the available data indicate that condominiums remained among the city’s more attainable ownership options during both years analyzed.
The City of Troutdale seal, featuring the community’s long-standing connection to the Columbia River and its identity as the “Gateway to the Gorge.” Photo: Abdur Abdul-Malik, Portland Appraisal Blog
Key Takeaways
Troutdale’s housing market is, for practical purposes, a detached-home market. Detached homes accounted for the overwhelming majority of residential sales activity during 2025 and remain the property type that most clearly defines local housing conditions.
The city’s housing stock is primarily composed of resale housing rather than new homes. No new construction detached-home sales were recorded during either 2024 or 2025. Among detached-home sales occurring during the two-year period, construction dates ranged from 1893 to 2022, with the average home built in 1989.
While attached homes and condominiums provide alternative ownership opportunities, both segments remain relatively small and generate limited annual transaction volume compared with detached housing. For buyers looking to take advantage of their comparatively lower prices, such units do not come on the market very often and may require patience.
For buyers seeking a balance between affordability, access to the Portland Region, and proximity to outdoor recreation, Troutdale remains a community worth considering. Located at the gateway to the Columbia River Gorge, the city offers a housing market that remains more attainable than many higher-priced areas within the metropolitan region.
Sources & Further Reading
All data presented in this annual snapshot is sourced directly from RMLS and has been subjected to a rigorous cleaning and validation process to ensure reliability for each single-family residential housing segment analysis. The trends, comparisons, and commentary are the result of original appraisal expertise and independent analysis—not aggregated from secondary sources or news summaries.
Thanks for reading—I hope you found a useful insight or an unexpected nugget along the way. If you enjoyed the post, please consider subscribing for future updates.
Are you an agent in Portland who wonders why appraisers always do “x”?
A homeowner with questions about appraiser methodology?
If so, feel free to reach out—I enjoy connecting with market participants across Portland and the surrounding counties, and am always happy to help where I can.
And if you’re in need of appraisal services in Troutdale or anywhere in the Portland Region, we’d be glad to assist.
About the Author — Abdur Abdul‑Malik, SRA, ASA
Abdur Abdul‑Malik is the founder, author, and publisher of the Portland Appraisal Blog, where he produces original regional and neighborhood‑level housing analytics for the Portland Region. He is a certified residential appraiser serving Oregon and Washington, drawing on RMLS transaction data, public records, and custom segmentation models he has built.
He developed the Portland Appraisal Blog Affordability Index (PABAI), a payment‑based affordability metric built from actual RMLS sales. PABAI incorporates weekly updates based on the prevailing 30‑year fixed mortgage rate, providing a locally grounded measure of housing affordability across the region.
At today’s 7.28% mortgage rate, the monthly principal‑and‑interest payment on a Q1 2026 Portland Region median‑priced detached home ($580,000) with 20% down is $3,175, up from $2,776 at February’s low. Lifetime interest rises to $678,908 and repricing all Q1 loans at today’s rate adds $492M in regional interest.
What Happened This Week
Mortgage rates surged higher this week, with the 30‑year fixed jumping to 7.28%—a 25 bps increase from last week’s 7.03% reading. This marks the sixth consecutive weekly increase, the fifth consecutive year‑to‑date high, and the highest mortgage rate recorded since November 22, 2023, when Freddie Mac reported a rate of 7.29%.
The table below shows where today’s rate sits within the 2026 range, including the February low, last week’s reading, and this week’s new year‑to‑date high.
Time Frame
Date
Rate
Rate Delta
YTD Low
February 26, 2026
5.98%
-1.30%
Last Week
September 24, 2026
7.03%
-0.25%
Current Week
October 1, 2026
7.28%
—
Mortgage rate context showing the year‑to‑date low, last week’s rate, and the current week’s rate. Rate Delta reflects the change relative to the current week (7.28%). January 1, 2026 – October 1, 2026 Primary Mortgage Market Survey® (PMMS®) Data: Freddie Mac | PortlandAppraisalBlog.com
The broader 2026 pattern remains intact: rates bottomed in late February, climbed sharply through early April, cooled briefly, and then resumed their upward drift beginning April 23. What began as a gradual rise over the summer has accelerated noticeably in recent weeks, culminating in a sharp move higher that pushed rates to the top of the 2026 range.
Affordability remains strained at these levels; rate changes become increasingly consequential as mortgage costs move higher. The move from 7.03% last week to 7.28% today meaningfully reduces purchasing power and raises monthly payment obligations for buyers already operating near qualification limits.
As the charts below show, today’s rate now sits at the very top of the 2026 range, and the Portland Appraisal Blog Affordability Index (PABAI) reflects the ongoing affordability pressures facing homebuyers throughout the Portland Region.
Weekly Rate Change (Basis Points)
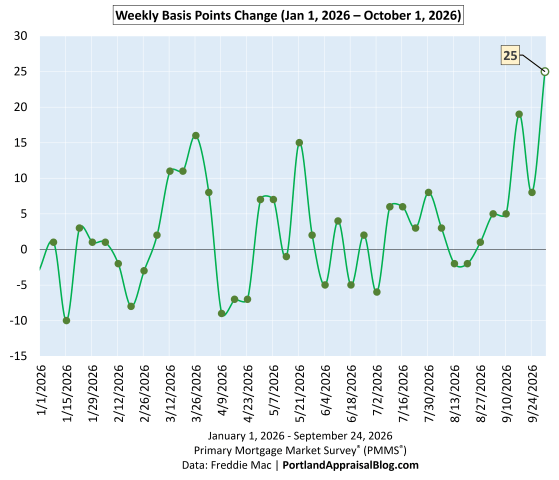
The chart below shows the weekly change in mortgage rates, not the actual mortgage rate. Values above the zero line indicate rates increased from the prior week, while values below the line indicate rates decreased. One basis point equals 0.01%.
This week’s takeaway: Mortgage rates increased by 25 basis points (0.25%), the largest weekly increase of 2026. The previous record increase occurred just two weeks ago, highlighting how rapidly rates have moved higher recently. Rates have now increased for six consecutive weeks, the longest streak of weekly increases this year.
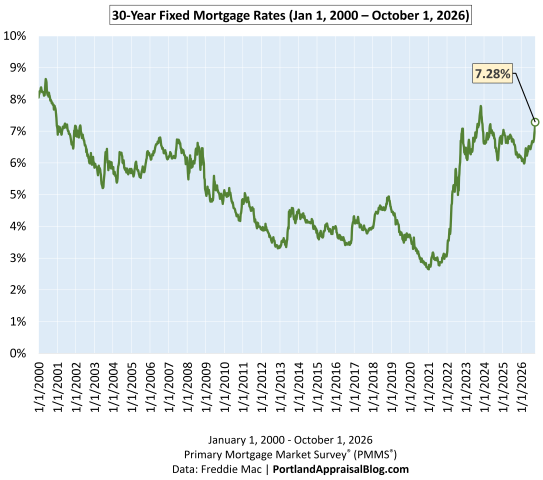
The long‑run chart shows how today’s rate fits into a 25‑year history of mortgage cycles. The early 2000s sat in the 6–8% range, the post‑Great Recession era brought a decade of unusually low rates, and the pandemic period pushed borrowing costs to historic lows. Years after leaving that ultra‑low‑rate environment, the market continues to adjust to more difficult financing constraints, and today’s 7.28% reflects that ongoing shift. While current rates remain well below the peaks seen in the early 2000s, they are elevated relative to most of the past two decades and have now returned to levels last seen in late 2023. Affordability continues to be shaped by the same structural pressures highlighted in the medium‑run and short‑run views.
Medium‑Run View (Since COVID)
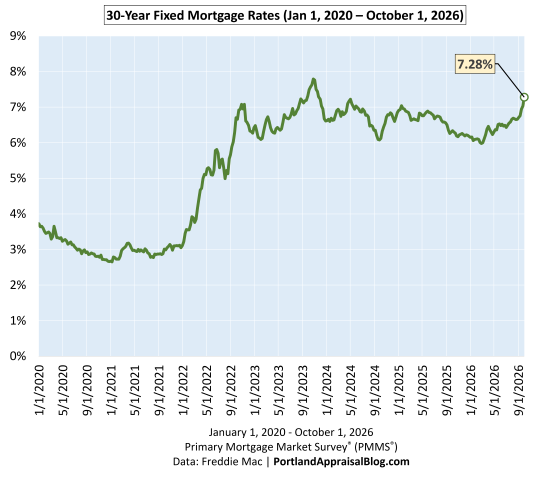
The COVID‑era chart highlights the dramatic rate compression of 2020–2021, the rapid surge of 2022, and the choppy plateau that has defined the past several years. Rates have generally oscillated between roughly 6% and 7% since mid‑2023, though today’s 7.28% has pushed above that range and returned borrowing costs to levels not seen since late 2023. Volatility has cooled compared to the sharp swings of 2022, but the medium‑run trend remains one of elevated and persistent borrowing costs, with the market continuing to adjust to structurally higher financing conditions across the Portland Region.
Short‑Run View (2026 YTD)
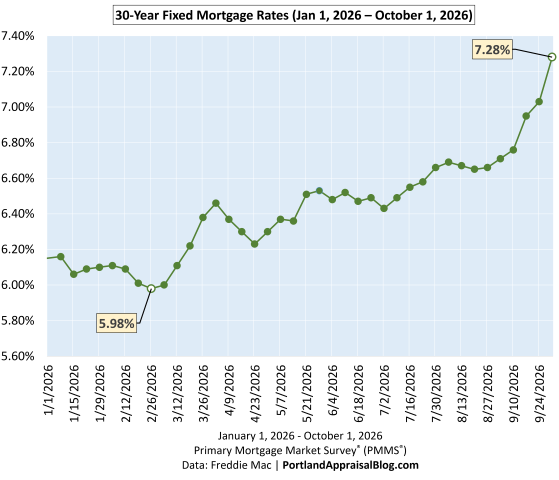
Note: The y-axis starts at 5.6% to allow better examination of weekly differences.
The year‑to‑date chart shows the full shape of the 2026 cycle: a clear bottom at 5.98% on February 26th, a sharp rise into early April, a brief cooldown, and a renewed climb that pushed rates into the mid‑6% range by late May. While rates spent much of the summer fluctuating within a relatively narrow band, the past month has seen a pronounced upward move. Today’s 7.28% reading marks a new year‑to‑date high and leaves rates 130 basis points above the February low.
Affordability now sits at its weakest point of 2026. The short‑run trend remains the most relevant for buyers today because it directly influences monthly payments, debt‑to‑income ratios, and qualifying power across the Portland Region. The recent surge higher underscores how quickly affordability conditions can deteriorate when mortgage rates rise, even without corresponding changes in home prices or household income.
Portland Appraisal Blog Affordability Index (PABAI)
What PABAI Measures
The Portland Appraisal Blog Affordability Index (PABAI) is a model that estimates how home sale prices compare to what a median‑income household can qualify for under standard lending assumptions (HUD Portland‑Vancouver‑Hillsboro MSA median income, 20% down, and a 28% DTI for principal, interest, taxes, insurance, and HOA dues).
Unlike national affordability indices, PABAI is built from actual RMLS transactions rather than a single hypothetical price point. It computes an affordability ratio for every closed sale in the Portland Region during the analysis period using rates matched to the date of close, reported taxes, reported HOA dues, and an insurance estimate based on a percentage of the home’s value. The individual affordability ratios are then averaged to produce the reported PABAI value for that period. For Q1 2026, this approach captures the actual mix of homes sold and the financing conditions present at the time those transactions occurred. Each housing segment—detached, attached, condos, and manufactured—is calculated separately, ensuring that segment‑specific dynamics are preserved rather than blended together. This approach provides a more detailed, locally grounded view of Portland‑area affordability and avoids the distortions that occur when fundamentally different housing types are combined into a single regional metric.
A PABAI of 100 means the market is exactly affordable at that income level (the Q1 2026 HUD median MSA income was $124,100 for a family of four). Values above 100 indicate excess qualifying capacity (more affordable), while values below 100 indicate a shortfall (strained affordability). Full methodology and the interpretation scale are available on the PABAI explainer page.
PABAI Range
Interpretation
120+
Strongly Affordable
100–119
Moderately Affordable
80–99
Strained
Below 80
Severely Constrained
Q1 2026: Actual vs. Constant‑Rate Affordability
Note: The y-axis starts at 65 to allow better examination of weekly differences.
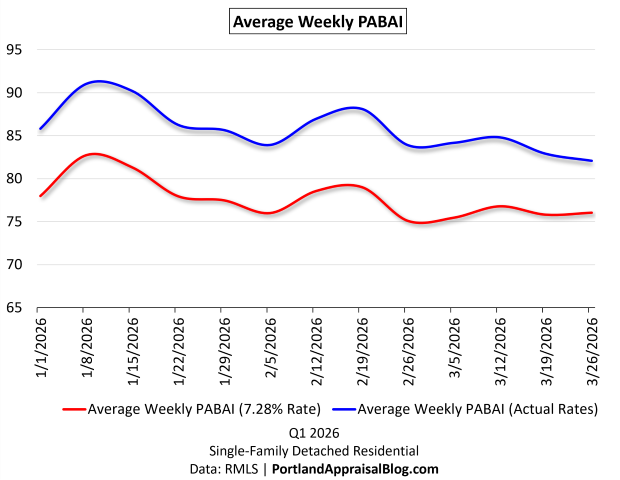
The Q1 chart compares two versions of PABAI: one using actual weekly mortgage rates, and one using today’s rate (7.28%) applied as a constant across the entire quarter. Because the constant‑rate line uses a rate that sits well above every mortgage rate observed during Q1, it consistently falls below the actual‑rate line throughout the entire period. That part isn’t the story.
The key insight is the size and persistence of the gap between the two lines. During Q1, buyers benefited from mortgage rates that ranged from 5.98% to 6.38%, substantially below today’s 7.28%. As a result, the actual‑rate PABAI readings exceed the constant‑rate equivalents every week, often by a wide margin.
The quarterly averages tell the story clearly: 85.45 under actual rates versus 77.35 under a constant 7.28% rate. In other words, if today’s financing environment had existed throughout Q1, affordability would have been materially worse despite identical home sales, taxes, HOA dues, and household income assumptions.
Today’s 7.28% rate pushes the constant‑rate line well below the actual‑rate line, illustrating how much affordability has deteriorated since the first quarter of the year. The comparison highlights the compounding effect of higher borrowing costs and shows how rapidly qualifying power can erode when mortgage rates move substantially above the levels that prevailed during Q1.
Structural Unaffordability and the Seasonal Pattern
Detached homes in the Portland Region remain structurally unaffordable to a household earning the HUD median MSA income. PABAI has been below 100 for years, and Q1 2026 continues that pattern. What the chart makes clear is that winter remains the best window for buyers on tight qualifying budgets: affordability improves when rates soften and seasonal pricing cools. As spring approaches, both rates and prices firm up, and affordability reliably compresses.
With the 30‑year fixed now at a new 2026 high of 7.28%, the separation between the two PABAI lines illustrates how much qualifying power has been lost since Q1. If today’s rate had prevailed throughout the quarter, average affordability would have fallen from 85.45 to 77.35, pushing the market deeper into constrained territory. The early‑year affordability advantage reflected in the actual‑rate series would have been meaningfully reduced.
Today’s 7.28% reading keeps affordability firmly in the severely constrained range and reinforces the sensitivity of housing qualification to mortgage rates. The current rate environment underscores how quickly affordability can deteriorate when financing costs rise while home prices remain elevated.
Affordability Snapshot (This Week)
Maximum Sustainable Payment (MSP) — Median Income
Understanding affordability begins with a simple anchor: how much housing payment a median‑income household in the Portland Region can sustainably carry. Using the Q1 2026 HUD median MSA income and applying a standard front‑end debt-to-income ratio, we can calculate the Maximum Sustainable Payment (MSP) that fits within traditional affordability guidelines. This number does not change with mortgage rates—it is tied purely to income and serves as the baseline against which all market payments are measured.
Affordability Metric
Value
Median MSA Income (Q1 2026)
$124,100
Qualifying Ratio (Front‑End)
28%
Max Sustainable Payment
$2,895.67
This ceiling is also the reason PABAI incorporates all components of monthly housing cost rather than focusing solely on principal and interest. As mortgage rates rise, interest consumes a larger share of the allowable payment “space,” leaving less room for taxes, insurance, HOA dues, and mortgage insurance. When these components collectively exceed the sustainable threshold, the buyer must either reduce the loan amount or shift to a lower‑priced segment of the market.
In practical terms, higher rates compress the principal that can be repaid within the same affordability boundary—which is why rising rates translate directly into fewer accessible homes and tighter qualifying margins.
Q1 2026 Affordability Recomputed at Today’s Rate
The table below shows how Q1 2026 affordability metrics change when all 3,349 detached sales are recalculated at this week’s 7.28% rate. This is the clearest way to see how rising rates reshape qualifying power, housing burden, and the share of homes accessible to a median‑income household.
Metric
Actual Q1 2026
Recomputed at 7.28% Rate
Change
Average PABAI
85.45
77.35
-8.10 pts
Required income (28% ratio)
$145,236
$160,437
+10.47%
Median‑income shortfall
17.03%
29.28%
+12.25 pts
Avg monthly mortgage pmt
$3,932.66
$4,340.92
+$408.26
Avg housing burden (DTI)
38.03%
41.98%
+3.95 pts
# of Affordable homes
967
576
-391 homes
% of homes affordable
28.87%
17.20%
-11.67 pts
Note: Required income and median-income shortfall are derived from PABAI, which is calculated using the affordability ratio of all sales in the dataset. Payment and housing-burden metrics are arithmetic averages and therefore will not reconcile directly through the 28% affordability threshold. Single-family Detached | Q1 2026 HUD Portland‑Vancouver‑Hillsboro MSA median income: $124,100 Data: RMLS (3,349 observations) | PortlandAppraisalBlog.com
Because today’s rate sits well above the mortgage rates that prevailed during Q1, the recomputed metrics show a substantial deterioration in affordability relative to the actual first‑quarter environment. Required income rises sharply, housing burden increases, and the number of homes affordable to a median‑income household falls dramatically.
The shift is visible across every metric. PABAI declines from 85.45 to 77.35, required income increases from $145,236 to $160,437, and the median‑income shortfall expands from 17.03% to 29.28%. Average monthly mortgage payments increase by more than $400 per month, while housing burden rises to nearly 42% of gross income, far above the benchmark 28% qualifying ratio used in the model.
Perhaps most striking, the number of homes affordable to a median‑income household falls from 967 to 576, eliminating 391 affordable homes from the Q1 dataset. The affordable share of the market drops from 28.87% to 17.20%, illustrating how quickly affordability can deteriorate when mortgage rates move higher and remain elevated.
How Rising Rates Reshape Affordability
Taken together, these metrics illustrate how mortgage rates influence affordability through multiple channels simultaneously. Higher rates do not merely increase monthly payments. They also increase the income needed to qualify, reduce borrowing capacity, and shrink the portion of the market accessible to median‑income households.
Higher rates reduce qualifying power, remove homes from the affordable inventory pool, and force buyers to make difficult tradeoffs between location, home size, housing type, and monthly payment. As financing conditions tighten, affordability becomes a constraint not just on how much buyers can spend, but on the range of housing options realistically available to them.
The Buyer‑Side Impact
For buyers, the experience varies by circumstance but the direction is the same. Households with limited financial flexibility tend to feel the tightening most acutely, as higher rates reduce qualifying power and narrow the range of homes available within budget. In many cases, buyers are forced to make tradeoffs involving location, home size, housing type, condition, or commute time in order to keep monthly payments manageable.
Move‑up buyers face a different challenge. While existing home equity may help offset some of the affordability pressure, higher mortgage rates increase the payment gap between a current home and the desired replacement property. As a result, the financial benefit of moving often becomes less clear, even when household income and equity positions remain strong.
Cash buyers, by contrast, can gain relative leverage when financing conditions become more restrictive. As affordability pressures reduce the pool of financed buyers, cash purchasers may encounter less competition in certain segments of the market. The effect, however, is not uniform and can vary significantly by price range and property type.
Across all buyer groups, elevated mortgage rates are influencing not only what buyers can afford, but also the choices they make and the segments of the market in which they can realistically compete.
The Seller‑Side Impact
Rising rates don’t just reshape the buyer experience—they influence seller outcomes as well. In the Q1 2026 detached market, cumulative days on market (CDOM) increased 11.26%, and the current rate environment suggests that upward pressure on market times may persist. As affordability tightens and the pool of qualified buyers shrinks, homes that would have moved quickly in a lower‑rate environment may begin to sit longer, particularly in segments where pricing is already stretched.
Today’s 7.28% rate places financing conditions at the most challenging level of 2026, reinforcing the same dynamic: fewer qualified buyers, more selective demand, and a market where pricing precision matters. This does not necessarily imply an abrupt market slowdown, but it does suggest sellers should expect a more deliberate buyer pool and be prepared for longer market times—especially in higher‑priced segments where buyer purchasing power is most sensitive to changes in mortgage rates.
TIP: Total Interest Paid — Why Small Rate Moves Matter
Total Interest Paid (TIP) is one of the clearest ways to understand how mortgage rates shape long‑run affordability. While buyers shop based on monthly payment, the lifetime cost of borrowing moves far more dramatically than the payment itself. Even small rate changes can add—or remove—tens of thousands of dollars in interest over the life of a loan.
At today’s 7.28% rate, the lifetime interest on a standard Portland Region purchase sits far above the levels buyers saw during the pandemic and substantially higher than the lows recorded earlier this year. The difference between a 5.98% environment and a 7.28% environment may appear manageable when viewed as a weekly rate chart, but over a 30‑year loan the additional interest compounds into a significant increase in total repayment. This is the type of change that can materially affect long‑run household finances across the Portland Region.
This is why TIP matters: it captures the hidden cost of rising rates. Buyers feel the payment, but the long‑run financial burden is embedded in the interest curve. As the charts below show, the 2026 rate path has pushed TIP to the highest levels of the year, even as monthly payment changes appear more gradual. The cumulative effect is what reshapes affordability—a dynamic that becomes especially clear when comparing TIP across different rate environments.
2026 YTD Total Interest Paid
Note: The y-axis starts at $480,000 to allow better examination of weekly differences.
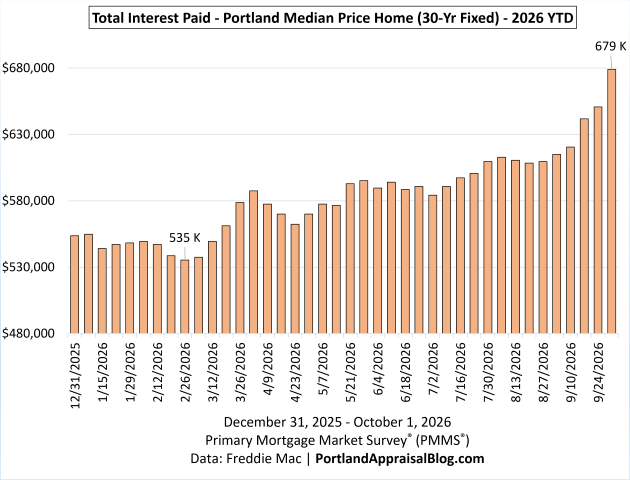
The 2026 YTD TIP chart shows how sharply lifetime borrowing costs have increased as mortgage rates moved higher throughout the year. These calculations are based on the total interest a buyer would pay on the Q1 2026 Portland Region median‑priced home of $580,000, assuming a 20% down payment and applying the rate effective in each week. This isolates the impact of rate movements alone, holding price and loan structure constant.
The low point came on February 26, when a 5.98% mortgage rate produced a total interest burden of $535,342. As rates moved higher through the spring and summer, TIP increased steadily, crossing $600,000 in July and continuing its upward climb into September.
Today’s 7.28% mortgage rate produces a total interest burden of $678,908, the highest reading of 2026. Compared with the February low, that represents an increase of $143,566 in lifetime interest—a change driven entirely by mortgage rates rather than home prices.
The shape of the chart makes the pattern unmistakable. Buyers naturally focus on the monthly payment, but the lifetime interest curve tells a different story. By spreading borrowing costs across a 30‑year loan term, even relatively small changes in mortgage rates accumulate into meaningful differences in total repayment. This long‑run perspective is what makes TIP such a useful complement to traditional affordability measures.
TIP per $1 Borrowed
Note: The y-axis starts at $1.00 to allow better examination of weekly differences.
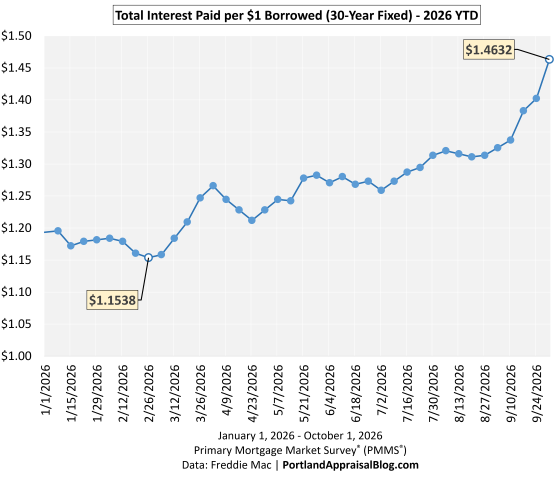
The TIP‑per‑$1 chart shows how much interest a buyer pays for every dollar borrowed at different mortgage rates. This is one of the clearest ways to visualize the long‑run cost of financing. At the year‑to‑date low of 5.98%, each dollar borrowed generated approximately $1.1538 in interest over the life of the loan. As rates moved higher throughout the year, that figure increased steadily, reflecting the growing cost of mortgage debt.
Today’s 7.28% rate produces $1.4632 of interest for every $1 borrowed, the highest reading of 2026. Put differently, a borrower would repay more in interest than in principal over the life of the loan. For example, a borrower financing $100,000 would pay roughly $146,320 in interest over the life of a 30‑year fixed mortgage held to maturity, resulting in a total repayment of approximately $246,320.
The chart highlights how the cumulative cost of borrowing has accelerated in recent weeks. While buyers often focus on monthly payment, the TIP‑per‑$1 metric illustrates the long‑run consequences of higher rates by converting abstract percentage changes into dollars and cents. As mortgage rates rise, each borrowed dollar carries a larger lifetime interest obligation, increasing the total cost of homeownership even when home prices remain unchanged.
Regional Interest Delta (RID)
The Regional Interest Delta (RID) models how much total lifetime interest the Portland Region’s Q1 detached‑home buyers would collectively pay when mortgage rates shift. To keep the metric consistent, RID assumes that all 3,349 Q1 detached sales were financed under standard 20%‑down, 30‑year conventional underwriting, even though the actual dataset includes cash purchases and loans under FHA, VA, jumbo, and other programs. Rates are matched to each home’s close date to reflect the real timing of rate movements, but individual buyers may have locked slightly different rates depending on their specific loan terms. This approach provides a clean, apples‑to‑apples way to measure how rate changes affect the region’s total interest burden.
Scenario
Rate
Total Lifetime Interest
RID
Actual Q1 2026 Pipeline
Actual rate matched to close date
$2,091,901,976
—
Modeled at Today’s Rate
7.28%
$2,584,122,740
+$492,220,764
The Regional Interest Delta (RID) is a modeled estimate assuming all Q1 2026 detached sales were financed under standard 20%-down, 30-year conventional terms. Actual loan terms may vary. Single-family Detached | Q1 2026 Data: RMLS (3,349 observations) | PortlandAppraisalBlog.com
Using those actual matched rates, the region’s Q1 2026 pipeline will generate $2,091,901,976 in lifetime interest. Recomputing the same loans at today’s 7.28% rate increases the total to $2,584,122,740. The difference—the Regional Interest Delta (RID)—is $492,220,764 in additional lifetime interest.
To put that number in perspective: $152 million is the estimated cost of hollywoodHUB, a 222‑unit affordable housing development in Portland. The current RID is more than three times that amount. In other words, applying today’s mortgage rate environment to a single quarter of Portland Region detached home sales generates nearly half a billion dollars in additional lifetime interest compared with the actual financing conditions buyers experienced during Q1.
RID makes the scale of rate changes unmistakable. What appears to be a modest change in mortgage rates at the household level becomes a massive financial shift when applied across thousands of loans. While buyers experience rising rates through higher monthly payments and reduced purchasing power, RID reveals the broader regional impact: a substantial increase in the long‑run cost of homeownership driven entirely by financing conditions rather than changes in home prices.
Payment Delta
The Payment Delta shows how monthly affordability shifts as mortgage rates move. Using the Q1 2026 Portland Region median‑priced home of $580,000 with a 20% down payment, the monthly principal‑and‑interest payment changes meaningfully even with small rate movements.
Date
Rate
Monthly P&I
Pmt Delta
Feb 26, 2026 – YTD Low
5.98%
$2,775.95
—
Sep 24, 2026 – Last Week
7.03%
$3,096.36
$320.41
Oct 1, 2026 – Current Week
7.28%
$3,174.74
$398.79
Payment Delta reflects the change from the year‑to‑date low on February 26. Monthly payment for home using median Q1 2026 detached home price ($580,000) and 20% down. Primary Mortgage Market Survey® (PMMS®) Data: Freddie Mac | PortlandAppraisalBlog.com
Monthly payments remain meaningfully higher than the February low and now sit well above the region’s Maximum Sustainable Payment (MSP) of $2,895.67. At the year‑to‑date low on February 26, a 5.98% mortgage rate produced a monthly principal‑and‑interest payment of $2,775.95, comfortably below the affordability ceiling.
Today’s 7.28% rate pushes that payment to $3,174.74, an increase of $398.79 per month relative to the February low and $279.07 above the MSP. This figure reflects principal and interest only; including taxes, insurance, HOA dues, and mortgage insurance (if applicable) would increase the monthly housing obligation further.
Today’s payment is nearly $400 per month higher than it was at the February low. For many households, finding an extra $400 every month is not a trivial adjustment. Higher housing costs often compete directly with discretionary spending, savings goals, retirement contributions, vacations, entertainment, and other components of the household budget.
While Payment Delta is smaller in scale than the lifetime borrowing costs shown in the TIP and RID sections, it is the metric buyers experience most directly. For many households, rising payments affect not only what they can afford, but also where they can buy and which housing options remain within reach.
Purchasing Power
The table below shows how purchasing power has changed since the year‑to‑date low, based on a range of monthly P&I budgets. At February’s 5.98% rate, buyers could finance meaningfully more than they can at today’s 7.28% rate.
Target Monthly P&I Budget
Purchasing Power at YTD Low Rate (5.98%)
Purchasing Power at 7.28% Rate
Change in YTD Low Purchasing Power
$2,000
$417,875
$365,384
-$52,491
$2,500
$522,344
$456,730
-$65,614
$3,000
$626,812
$548,076
-$78,737
$3,500
$731,281
$639,421
-$91,859
$4,000
$835,750
$730,767
-$104,982
$4,500
$940,218
$822,113
-$118,105
$5,000
$1,044,687
$913,459
-$131,228
$5,500
$1,149,156
$1,004,805
-$144,351
$6,000
$1,253,624
$1,096,151
-$157,473
Purchasing power comparison assumes 20% down and reflects principal and interest (P&I) only. Calculations use the YTD low rate (5.98%) and this week’s rate (7.28%) across common monthly P&I budgets. Actual purchasing power is lower once taxes, insurance, and HOA dues are included. Rates are based on the Primary Mortgage Market Survey® (PMMS®) Data: Freddie Mac | PortlandAppraisalBlog.com
Purchasing power has fallen by $52,491 to $157,473 since the year‑to‑date low, depending on the monthly budget. For many buyers in the Portland Region—especially those shopping near the Q1 2026 median price of $580,000—the relevant range is often $2,500 to $3,000 in monthly principal‑and‑interest payments. Within that range, purchasing power has declined by approximately $65,614 to $78,737, highlighting how rising rates reduce borrowing capacity even when household income remains unchanged.
It’s also important to remember that these figures reflect principal and interest only. Actual purchasing power is lower once property taxes, insurance, HOA dues, and other housing costs are included. These expenses can further reduce the effective price range available to buyers.
The practical effect is straightforward: buyers can qualify for less house than they could earlier in the year. A household that could support a given monthly payment in February can now finance substantially less at today’s rate. That shift often forces buyers to make tradeoffs involving location, home size, condition, or housing type, even if their budget has not changed.
For sellers, declining purchasing power can translate into softer demand at certain price points and increased sensitivity to pricing. As financing capacity contracts, buyers become more selective and may seek concessions, credits, or rate buydowns to offset the impact of higher borrowing costs.
Payment Milestones
The table below shows the key payoff milestones for a loan originated this month, with the first payment due on the first of next month. Each milestone reflects how much of the loan has been repaid and how much interest has accrued by that point at today’s 7.28% rate.
Milestone
% of Loan Paid
Calendar Date
Interest Paid to Date
Early Equity
10%
Oct-2034
$258,088
Quarter Paid
25%
Oct-2041
$454,590
Half Paid
50%
Oct-2048
$604,630
Three-Quarters
75%
May-2053
$663,676
Payment milestone assumptions: Schedule assumes a loan originated in October 2026 with the first payment due November 1, 2026. Amortization is based on the Q1 2026 detached median price ($580,000) with 20% down, using the current 7.28% rate from the Primary Mortgage Market Survey® (PMMS®) Data: Freddie Mac | PortlandAppraisalBlog.com
These milestones illustrate how interest‑heavy the amortization schedule remains at today’s 7.28% rate. A borrower does not reach 10% equity through principal repayment alone until October 2034, after approximately $258,088 in cumulative interest has already been paid. The loan is not 50% repaid until October 2048, by which point total interest paid reaches approximately $604,630.
The pattern reflects a fundamental characteristic of fixed‑rate mortgage amortization: interest dominates the early years of the loan, while principal reduction accelerates later in the schedule. By the time the loan reaches the 75% repaid milestone in May 2053, most lifetime interest has already been paid and the remaining payments are increasingly directed toward principal.
These milestones help explain why mortgage rates have such a powerful influence on long‑run affordability. Higher rates increase the share of each early payment devoted to interest, slowing principal reduction and extending the time required to build meaningful equity through amortization alone.
Closing Thoughts
The story of this week is straightforward: mortgage rates have continued their climb, pushing the 30‑year fixed to 7.28%, the highest reading of 2026 and the highest level since November 2023. The effects are visible across every major affordability metric. The Portland Appraisal Blog Affordability Index (PABAI) continues to signal structural strain for median‑income households, while the recalculated Q1 data illustrates how higher financing costs reduce qualifying power, increase housing burden, and shrink the share of homes accessible to a typical buyer.
For buyers, the takeaway is simple: affordability conditions have become increasingly restrictive. The Purchasing Power analysis shows that buyers can afford substantially less house than they could at the February rate low, even when their monthly budget remains unchanged. The Payment Delta illustrates the same challenge from another angle, with the monthly payment on a median‑priced home now nearly $400 higher than it was at the year‑to‑date low. For many households, higher housing costs compete directly with discretionary spending, savings goals, retirement contributions, vacations, entertainment, and other components of the household budget.
For sellers, the implications are more nuanced but no less important. Reduced purchasing power and higher monthly payments mean buyers often become more selective and increasingly sensitive to pricing. Homes that are appropriately priced and well positioned within their market segment can still attract demand, but elevated financing costs leave less room for error than in lower‑rate environments.
The broader lesson is that mortgage rates influence affordability in multiple ways simultaneously. Higher rates increase monthly payments, reduce purchasing power, delay equity accumulation, and expand the long‑run cost of borrowing. Whether viewed through PABAI, Payment Delta, TIP, RID, Purchasing Power, or the Payment Milestones analysis, the conclusion remains consistent: the Portland Region is operating under the most restrictive financing conditions of 2026—and buyers, sellers, and market participants are all adapting to that reality.
Sources & Further Reading
All data presented in this weekly mortgage rate update is based on the Q1 2026 detached homes segment. The data is sourced directly from RMLS and has been subjected to rigorous cleaning and validation processes to ensure reliability for detached single-family residential analysis in the six-county Portland Region. The trends, comparisons, and commentary are the result of original appraisal expertise and independent analysis—not aggregated from secondary sources or news summaries.
Freddie Mac Primary Mortgage Market Survey® (PMMS®): Dataset
Portland Region Housing Affordability Snapshot – Rates Hit YTD High of 7.03% (September 24, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Soar to YTD High of 6.95% (September 17, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Hit YTD High of 6.76% (September 10, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Hit YTD High of 6.71% (September 3, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Return to 6.66% (August 27, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Dip to 6.65% (August 20, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Dip to 6.67% (August 13, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Hit YTD High of 6.69% (August 6, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Hit YTD High of 6.66% (July 30, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Hit YTD High of 6.58% (July 23, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Hit YTD High of 6.55% (July 16, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Return to 6.49% (July 9, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Drop to 6.43% (July 2, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Nudge Upwards to 6.49% (June 25, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Dip to 6.47% (June 18, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Climb to 6.52% (June 11, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Dip to 6.48% (June 4, 2026): Portland Appraisal Blog
Portland Region Housing Affordability Snapshot – Rates Rise to 6.53% (May 28, 2026): Portland Appraisal Blog
Coda
Thanks for reading—I hope you found a useful insight or an unexpected nugget along the way. If you enjoyed the post, please consider subscribing for future updates.
Are you an agent in Portland who wonders why appraisers always do “x”?
A homeowner with questions about appraiser methodology?
If so, feel free to reach out—I enjoy connecting with market participants across Portland and the surrounding counties, and am always happy to help where I can.
And if you’re in need of appraisal services in Portland or anywhere in the Portland Region, we’d be glad to assist.
About the Author — Abdur Abdul‑Malik, SRA, ASA
Abdur Abdul‑Malik is the founder, author, and publisher of the Portland Appraisal Blog, where he produces original regional and neighborhood‑level housing analytics for the Portland Region. He is a certified residential appraiser serving Oregon and Washington, drawing on RMLS transaction data, public records, and custom segmentation models he has built.
He developed the Portland Appraisal Blog Affordability Index (PABAI), a payment‑based affordability metric built from actual RMLS sales. PABAI incorporates weekly updates based on the prevailing 30‑year fixed mortgage rate, providing a locally grounded measure of housing affordability across the region.